


Changes to the revenue threshold for reporting country-by-country profits are a matter of particular interest to many parent companies in Vietnam and multinational corporations. Decree 255/2026/ND-CP Officially replacing Decree 132/2020/ND-CP from July 1, 2026, the familiar VND 18,000 billion threshold, maintained for many years, raises numerous questions about whether businesses are still required to file reports, the timing of threshold determination, and the responsibility to notify the tax authorities. This article systematically reviews the legal basis, the method of determining the new threshold, and immediate actions needed to avoid delays or omissions in tax declaration obligations.
Why is changing the revenue threshold for reporting country-by-country profits noteworthy for companies with related-party transactions?
Changing the revenue threshold for reporting international earnings is not simply a technical adjustment of the numbers. It represents a shift from setting the threshold as an absolute amount in Vietnamese Dong to setting it according to international practice, calculated in Euros and subject to annual exchange rate conversion.
For parent companies in Vietnam that are close to the boundary of the old threshold, or businesses with parent companies abroad, failure to keep up with the new regulations can lead to two opposing scenarios: either missing reporting obligations even though they are actually subject to them, or wasting resources preparing documentation for an obligation that the business no longer needs to fulfill.
In the context of global tax authorities increasingly tightening information exchange under multilateral mechanisms, understanding changes in the revenue threshold for reporting country-by-country profits is the first step for businesses to proactively review all their obligations to declare related-party transactions for the entire group, instead of just dealing with each legal entity individually in Vietnam.
The old threshold according to Decree 132/2020/ND-CP
Prior to July 1, 2026, according to point a, clause 5, Article 18 of Decree 132/2020/ND-CP, the threshold for preparing the Country-by-Country Profit Report was stipulated for taxpayers that are the ultimate parent company in Vietnam with consolidated global revenue of VND 18,000 billion or more during the tax period. This was a fixed threshold in Vietnamese Dong, not linked to exchange rates or international practices, and remained in place throughout the period of application of Decree 132/2020/ND-CP.
New thresholds according to Decree 255/2026/ND-CP
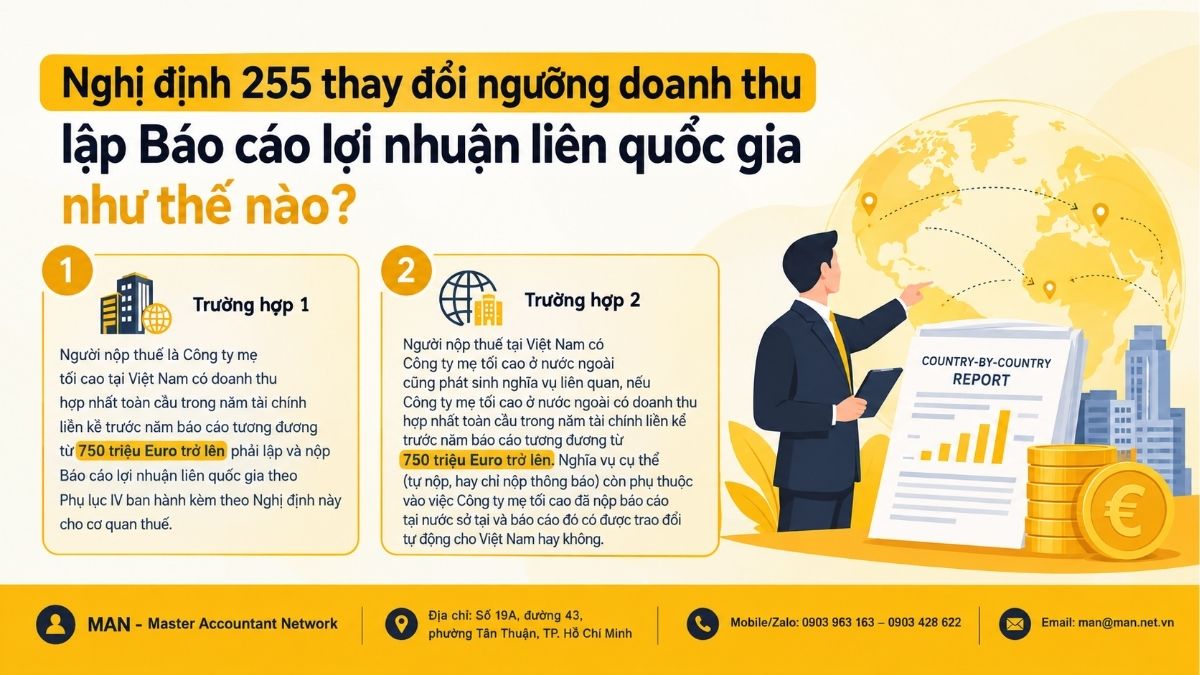
This is the core content of the change in the revenue threshold for preparing the Country-by-Country Report. According to Clause 1, Article 19 of Decree 255/2026/ND-CP, taxpayers who are the ultimate parent company in Vietnam with consolidated global revenue in the fiscal year immediately preceding the reporting year equivalent to 750 million Euros or more must prepare and submit the Country-by-Country Report as per Appendix IV issued with this Decree to the tax authorities.
Thus, the change in the revenue threshold for reporting country-by-country profits is clearly reflected in two points: a shift from the absolute amount of VND 18,000 billion to the equivalent of €750 million, in accordance with OECD practice, and a shift in the revenue determination threshold from "tax period" to "the fiscal year immediately preceding the reporting year." This second change, though less noticed, directly affects businesses, requiring them to refer to the data from the preceding year, rather than the current reporting year, when determining whether they qualify.
Legal basis and method for determining changes to the revenue threshold for preparing the Country-by-Country Report.
Article 19 of Decree 255/2026/ND-CP stipulates the responsibilities of taxpayers.
All provisions related to changes in the revenue threshold for preparing the Country-by-Country Report are stipulated in Article 19 of Decree 255/2026/ND-CP, specifically the clause on taxpayer responsibilities related to the Country-by-Country Report. Clause 1 of this article clearly states:
Taxpayers that are the ultimate parent company in Vietnam with consolidated global revenue in the fiscal year immediately preceding the reporting year equivalent to 750 million Euros or more must prepare and submit a Country-by-Country Report in accordance with Appendix IV issued with this Decree to the tax authorities.
Clause 2 of Article 19 expands the scope to include cases where taxpayers in Vietnam have a parent company located abroad. Accordingly, if the parent company abroad has consolidated global revenue in the fiscal year immediately preceding the reporting year equivalent to 750 million Euros or more, the taxpayer in Vietnam also incurs related obligations, although the specific obligation (self-payment or just notification submission) depends on whether the parent company has submitted its report in its home country and whether that report has been automatically exchanged with Vietnam.
Who will be affected by the change in the revenue threshold for reporting international earnings?
There are two groups of businesses that need to review their operations immediately when the revenue threshold for reporting country-by-country results takes effect:
- Group 1 – Ultimate parent company located in Vietnam: This group is directly subject to Article 19, paragraph 1, and must compare its consolidated global revenue for the fiscal year immediately preceding the reporting year against the €750 million threshold to determine its reporting obligations.
- Group 2 – Businesses in Vietnam with a parent company located abroad: This group does not directly compare its own revenue, but needs to know the consolidated global revenue of the entire corporation to determine whether the ultimate parent company overseas exceeds the €750 million threshold, thereby determining its reporting and notification responsibilities, or whether it is exempt under specific conditions.
Why is the €750 million figure linked to the CbCR automatic information exchange mechanism?
The shift to the €750 million threshold is not a random number. This threshold has been uniformly adopted by many countries and territories within the framework of the OECD's action against tax base erosion and profit shifting, ensuring that the country-by-country profit report of the same corporation is consistently identified regardless of the country in which it is submitted.
This changes the revenue threshold for preparing Country-by-Country Profit and Loss Statements in Vietnam, while also facilitating the exchange of reports between tax authorities. CbCR automatic information exchange mechanism According to the Agreement of the competent authorities, instead of each country requiring separate direct submissions.
Specific responsibilities of taxpayers after the revenue threshold for filing the Country-by-Country Report changes.
Understanding the new threshold is only the first step. Article 19 of Decree 255/2026/ND-CP also stipulates a series of accompanying responsibilities that businesses need to fulfill in the correct order.
Cases where reporting to the Vietnamese tax authorities is not required.
Taxpayers in Vietnam whose ultimate parent company abroad exceeds €750 million are not required to submit a Country-by-Country Report to the Vietnamese tax authorities in two cases:
- The ultimate parent company is obligated to prepare and submit reports in the country or territory of its residence, and these reports are automatically exchanged with the Vietnamese tax authorities in accordance with the Agreement of the competent authorities;
- The ultimate parent company designates an organization to file reports on its behalf in the country or territory where the organization is located, provided that the country has regulations requiring reporting, has a valid agreement with Vietnam from a competent authority, is not subject to systematic information exchange, and the representative organization has completed the notification procedures in accordance with the laws of the host country.
In both of the above cases, taxpayers in Vietnam are still required to submit a Notice of Entity to File the Country-by-Country Report on Income to the Vietnamese tax authorities.
Cases where reports must be submitted to the Vietnamese tax authorities.
Conversely, taxpayers in Vietnam are only required to submit a Country-by-Country Report in one of the following situations: the ultimate parent company is not obligated to prepare and submit the report in its place of residence; the country where the ultimate parent company resides has an international treaty or agreement with Vietnam but does not have an Agreement from a competent authority in effect at the time of its deadline; or that country has an Agreement but is in a state of not systematically exchanging information and this situation has been notified to the taxpayer in Vietnam.
Remarkable: Taxpayers are not required to report in situations where the ultimate parent company is not obligated to report in its home country solely due to differences in revenue thresholds, currencies, or revenue determination principles between countries, provided that the consolidated global revenue itself, as reported in the consolidated financial statements, is below the threshold prescribed in that country.
Notification regarding the reporting entities
Regardless of whether they are required to report or are exempt, taxpayers are obligated to submit the Notification of Entity to Report International Profits using Form No. 01/TB-BCLN issued with Decree 255/2026/ND-CP.
From the effective date of the Decree, this notification only needs to be submitted once when the obligation first arises, no later than the end of the fiscal year of the ultimate parent company of the reporting year. If there are any changes to the information compared to the most recently submitted notification, including in the case of termination of the obligation, the enterprise must update the information within 90 days from the date the change occurs.
In cases where a corporation has more than one taxpayer in Vietnam, the ultimate parent company may issue a document designating a single taxpayer to be responsible for submitting the notification as well as the Country-by-Country Report (if applicable).
The term, format, and exchange rate determine the threshold.
Three key milestones businesses need to remember:
- Deadline for submitting reports: No later than 12 months from the end of the fiscal year of the ultimate parent company of the reporting year.
- Submission format: The country-by-country profit report is submitted in encrypted XML format, and together with the Notice is submitted through the Tax Management Information System.
- Exchange rate: The foreign exchange rate used to determine the consolidated revenue threshold is determined according to the central exchange rate or the average cross-exchange rate of December of the year preceding the reporting year, as published by the State Bank of Vietnam.
This exchange rate mechanism is what makes the revenue threshold for reporting country-by-country profits dynamic from year to year: with the same revenue in Vietnamese Dong, a company can be above or below the 750 million Euro threshold depending on the reference exchange rate of the preceding December.
What should businesses do before the change in revenue thresholds for reporting country-by-country profits?
Step 1: Identify the company's role within the group.
Businesses need to clearly define whether they are the ultimate parent company in Vietnam or a subsidiary with an ultimate parent company abroad, as these two roles lead to two completely different sets of obligations according to Article 19 of Decree 255/2026/ND-CP.
Step 2: Compare consolidated global revenue to the €750 million threshold.
Take the consolidated global revenue figures for the fiscal year immediately preceding the reporting year, convert them using the central exchange rate or the average cross-exchange rate for December of that year as published by the State Bank of Vietnam, and compare them with the 750 million Euro threshold to determine whether the change in revenue threshold for reporting country-by-country profits applies.
Step 3: Review reporting obligations or exemption conditions.
For businesses with a parent company located abroad, it is necessary to gather information on whether the parent company has filed reports in its home country, whether that country has a valid Agreement with Vietnam by competent authorities, and whether it is on the list of countries experiencing disruptions in information exchange.
Step 4: Prepare and submit Notification Form No. 01/TB-BCLN on time.
Upon the first occurrence of the obligation, the enterprise must submit a notification no later than the end of the fiscal year of the ultimate parent company of the reporting year, and establish a periodic review process to update the notification within 90 days if any changes occur.
Step 5: Prepare a properly formatted Country-by-Country Report of Profit and Loss if required.
If the conclusion is that the business is required to submit a report to the Vietnamese tax authorities, the business needs to prepare the data according to Appendix IV, export it in encrypted XML format, and submit it through the Tax Management Information System within 12 months from the end of the fiscal year of the ultimate parent company.
For corporations with complex, multi-tiered ownership structures, accurately determining obligations based on changing revenue thresholds for reporting international earnings often requires significant time spent cross-referencing original foreign-language documents and regulations from each relevant country. This is where the problem lies. related party transaction advisory services This helps to enhance the role of the organization, shortening the review time and reducing the risk of incorrectly identifying roles within the group.
The relationship between changes in the revenue threshold for reporting cross-country profit and transfer pricing documentation.
The Country-by-Country Report is only one of three components of the conventional three-tiered related-party transaction documentation (Country Document, Global Document, Country-by-Country Report). Changing the revenue threshold for the Country-by-Country Report does not alter the obligation to prepare the Country Document and Global Document, which are determined according to separate criteria in Decree 255/2026/ND-CP.
Therefore, businesses that are not required to submit a Country-by-Country Report based on the €750 million threshold may still need to complete a Country Profile if related-party transactions occurred during the period and are not exempt from the requirement.
Conversely, for corporations exceeding €750 million, preparing a Country-by-Country Report often requires a review of consistency between profit allocation data by country and data in the country and global records to avoid discrepancies when tax authorities cross-check data through information exchange mechanisms. Businesses should consider this information. related party transaction documentation service From specialized, experienced units like MAN – Master Accountant Network, the process ensures consistency across all three components, rather than handling each report separately, guaranteeing the uniformity of the entire set of documents when requested.
Conclude
The change in the revenue threshold for reporting international profits under Decree 255/2026/ND-CP represents a shift from a fixed amount of VND 18,000 billion to €750 million, aligning with international practices and the exchange rate conversion mechanism for each fiscal year. This is not just a new number to remember, but also a whole series of responsibilities that come with it:
- Define your role within the corporation;
- Compare revenue figures according to the correct period and exchange rate;
- Determine the conditions for exemption or obligation to submit reports;
- And the obligation to submit the Notice must not be neglected, regardless of the final conclusion.
Businesses with a parent company based in Vietnam or that are members of a multinational corporation should review their obligations now, instead of waiting until close to the 12-month deadline from the end of the fiscal year to begin determining their liabilities.
If your business is still unsure whether it falls under the scope of changes to the revenue threshold for reporting cross-country profit, MAN – Master Accountant Network's team of related-party transaction experts is ready to work with you to review your corporate structure, reconcile data, and complete the necessary documentation before the submission deadline.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network. He is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about Changes to the Revenue Threshold for Reporting International Profit and Loss Statements
When will the changes to the revenue threshold for reporting country-by-country profits take effect?
From July 1st, 2026, according to Decree 255/2026/ND-CP replacing Decree 132/2020/ND-CP, the threshold for preparing a Country-by-Country Profit Report will be raised from VND 18,000 billion to the equivalent of €750 million.
The €750 million threshold was determined based on revenue figures from which year?
Based on consolidated global revenue for the fiscal year immediately preceding the reporting year, not revenue for the reporting year itself.
Are businesses with a parent company located abroad required to submit a Country-by-Country Report of Profits to the Vietnamese tax authorities?
Not by default. If the ultimate parent company has already submitted a report in its home country and the report is automatically exchanged with Vietnam under an agreement with the competent authority, the enterprise in Vietnam only needs to submit a Notification, not a report.
Which exchange rate is used to convert revenue to Euros when determining the threshold?
The central exchange rate or the average cross-exchange rate for December of the year preceding the reporting year, as published by the State Bank of Vietnam.
Information regarding which entities are required to submit the Country-by-Country Report and when.
According to Form No. 01/TB-BCLN issued with Decree 255/2026/ND-CP, the information must be submitted once when the obligation first arises, no later than the end of the fiscal year of the parent company of the reporting year; if there are any changes to the information, it must be updated within 90 days from the date the change occurs.
What is the deadline for submitting the Country-by-Country Report?
No later than 12 months from the end of the fiscal year of the ultimate parent company of the reporting year, submit in encrypted XML format via the Tax Management Information System.