





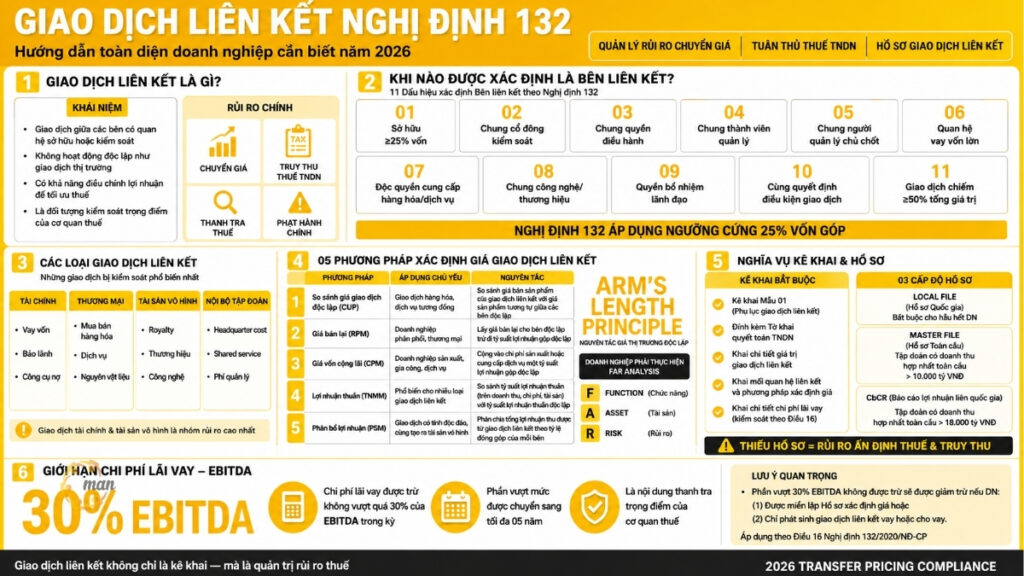
Related-party transactions under Decree 132 are one of the most complex tax areas, directly impacting corporate income tax obligations and transfer pricing risks. From identifying related parties and conducting functional, asset, and risk analysis (FAR analysis) to selecting market pricing methods, every step requires absolute precision and strict adherence to regulations. Decree 132/2020/ND-CP.
This article summarizes all key regulations, implementation guidelines, declaration obligations, documentation requirements, and practical experiences to help businesses minimize audit risks, optimize taxes, and ensure legal compliance. For businesses requiring more in-depth support, please refer to this information. related party transaction advisory services This will help assess risks and develop more effective compliance plans.
What is affiliate trading? Understanding its nature
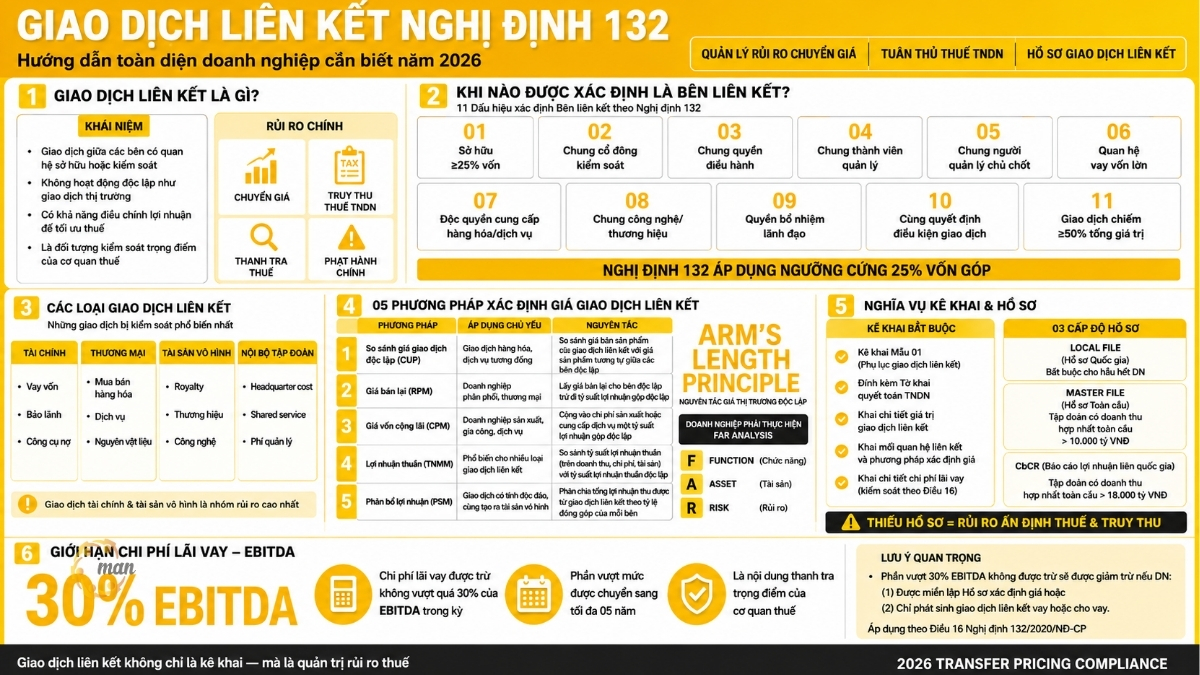
Related-party transactions under Decree 132 are not ordinary buying and selling transactions. These are transactions arising between two or more parties that have a relationship of ownership, control, or management over each other.
The nature of related-party transactions under Decree 132 is that because the parties do not act independently, prices and transaction conditions can be manipulated to achieve economic objectives, most commonly by transferring profits to areas with lower tax rates (also known as transfer pricing).
The difference between normal transactions and related-party transactions according to Decree 132.
The difference between related-party transactions under Decree 132 and normal transactions is that if a business purchases goods from an independent partner, the price will be determined by market supply and demand.
However, if a business purchases from its parent company, the price may be set higher (to reduce the subsidiary's profit in Vietnam) or lower (for other purposes). This difference is what makes related-party transactions under Decree 132 subject to strict regulation.
Why do businesses engaging in related-party transactions need to strictly comply with Decree 132/2020/ND-CP?
In fact, Decree 132 sets out two core responsibilities that every business with related-party transactions cannot ignore, namely:
- Declaration and Documentation Obligation: Businesses are required to declare these transactions and, in many cases, must prepare documentation. Transfer pricing determination dossier.
- Risk of Audits and Tax Collection: If the tax authorities discover that the transfer pricing does not comply with the arm's length principle, the business will have its taxable income adjusted upwards, leading to the collection of corporate income tax and administrative penalties.
So, how can businesses manage and minimize corporate income tax risks and avoid adjustments to taxable income? The first and fundamental step, which determines the entire process of complying with Decree 132 on related-party transactions, is correctly and fully identifying who the related parties are and which transactions are considered related-party transactions as stipulated in Clause 2, Article 5 of Decree 132/2020/ND-CP.
Identifying Related Parties and Related-Party Transactions under Decree 132
To comply with the regulations on related-party transactions under Decree 132, the most important first step is to accurately identify who the related parties are and which transactions constitute related-party transactions.
Portrait of the Affiliate as prescribed in Decree 132
The determination of the Affiliated Party is regulated in detail and fully in Clause 2, Article 5 of Decree 132. The following are specific cases:
- An enterprise directly or indirectly holds at least 25% of the equity of the owner of the other enterprise.
- Both enterprises have at least 25% of owner's equity held directly or indirectly by a third party.
- Businesses are managed and controlled in terms of business or financial decisions by an individual or organization, or this individual or organization has the right to appoint a majority of the members of the Board of Directors of both businesses.
- Two companies have more than 50% members of the Board of Directors (Board of Members, etc.) appointed by the same third party, or have family relationships (spouse, parents, children, siblings) between key members.
- Two businesses must have at least one person holding a key management position (e.g., Director, General Director, Deputy Director, etc.) or having a significant influence on business or financial decision-making.
- One business lends capital to another business in any form (including guarantees), provided that the loan represents at least 25% of the owner's equity and exceeds 50% of the total value of the borrower's operating assets.
- One business provides goods or services exclusively to another business, or together they control the consumer market or supply source through an agreement.
- One party uses, sells, or transfers the technology, trademarks, or intellectual property rights of the other party; or both parties are subject to control of the technology or trademarks by a third party.
- One party has the right to appoint members of the Board of Directors, the Management Board, or other management positions that have the authority to determine the other party's business policies.
- The two businesses have a decisive relationship or jointly decide on the terms of the transaction arising between them.
- One party engages in purchase, sale, or exchange transactions with the other party that account for 50% of the total value of goods and services generated by each party during the tax period (applicable in cases where the transaction does not comply with the principle of independence).
Important Note: Decree 132 sets the capital contribution threshold at 25% as a rigid basis for determining related-party relationships in various cases. Reviewing the ownership structure at the end of the tax period is mandatory. Cases involving borrowing are among the most complex criteria and are most prone to transfer pricing risks.
Classification of common types of related-party transactions under Decree 132
Any transactions arising between related parties are related-party transactions and are subject to the regulations of Decree 132/2020/ND-CP. Common types of related-party transactions covered by Decree 132 include:
| Affiliated trading group | Transaction details | Note |
| Financial Affiliate Transactions | Borrowing or lending capital between related parties Loan guarantee Providing debt instruments | Directly related to the 30% EBITDA interest expense limit under Article 16 of Decree 132. |
| Commercial affiliate transactions | Buying and selling goods Purchasing raw materials and finished products. Providing or renting services (excluding financial and banking services). | The most common type of related party transaction, usually using the CUP, RPM or TNMM method. |
| Invisible Affiliate Transactions | Transfer of rights to use or ownership of intangible assets (brands, technology, copyrights) Royalty Fee Management fee. | This group is most at risk of being audited by tax authorities because it is difficult to determine market value. |
| Internal link transactions | Sharing corporate management costs Headquarter Costs Internal support services | The business must demonstrate that it has received a real benefit and charge on the independence principle. |
Related transactions in enterprises are not only diverse in form but also clearly different in complexity and tax risks. In particular, Financial related transactions are often subject to the strictest supervision due to their direct impact on interest expenses according to Article 16 of Decree 132/2020/ND-CP. In addition, commercial, intangible and internal service transactions all require enterprises to have a complete valuation dossier, proving the nature and value of the transaction in accordance with the independence principle to minimize tax risks and comply with the law.
Methods for determining transfer pricing Decree 132
The core objective of Decree 132 on related-party transactions is to ensure that the prices of related-party transactions are determined based on the principle of independent market pricing (Arm's Length). To achieve this, businesses must select and apply appropriate pricing methods.
Principles for Determining the Independent Market Price (Arm's Length)
To demonstrate that related-party transactions are conducted as standalone transactions, a business must find equivalent transactions between unrelated parties and compare their economic and financial conditions.
The criteria for selecting comparison objects are as follows:
- Internal independent transaction comparison: This refers to comparing similar transactions performed by the same company with those of an independent third party.
- Compare independent external transactions: Similar transactions between two other independent third parties.
Comparisons must ensure similarity in terms of Function, Assets, Risk (FAR Analysis), contractual conditions, economic conditions, and business strategies.
Applying the 5 methods for determining transfer pricing as stipulated in Decree 132.
Decree 132/2020/ND-CP stipulates five basic methods, classified into traditional methods and profit-making methods:
| Method | Mainly applied | Principle |
| Compare Independent Transaction Prices (CUP) | Trading similar goods and services. | Compare the selling price of the product of the related transaction with the price of similar products between independent parties. |
| Resale Price (RPM) | Distribution and trading businesses create little added value. | Take the resale price to the independent party minus the independent gross profit margin. |
| Cost plus profit (CPM) | Manufacturing, processing and service providing enterprises. | Add an independent gross profit margin to the cost of production or service provision of the associated transaction. |
| Net Profit (NPP) | Popular for many types of affiliate deals. | Compare the net profit margin (on revenue, costs, assets) of the related transaction with the independent net profit margin. |
| Profit Distribution Metric (PSM) | Affiliated transactions are unique and create intangible assets. | Divide the total profit earned from the related party transaction according to the contribution ratio of each party. |
Choosing which method to use to determine the transfer pricing under Decree 132 is a complex process. Businesses need to conduct Functional Analysis (FAR) to determine their role (purely manufacturing, distributing low risk, or holding high risk).
Obligation to declare and prepare documentation for price determination.
Compliance with the regulations on related party transactions of Decree 132 is demonstrated through two main obligations: Declaration and Documentation.
Annual declaration of related-party transactions
Businesses that have related-party transactions during the tax period are required to declare information about these transactions and related parties in their Corporate Income Tax return. Related Party Transaction Appendix, even if they are exempt from preparing a Price Determination File.
- Required form: Businesses must use Form 01 (Appendix on related-party transactions attached to the Corporate Income Tax Return).
- Important details: Form 01 requires the declaration of the total value of related-party transactions, the relationship between the two parties, the pricing method, and especially interest expense (to control the limit according to Article 16). Declaring Form 01 is the first step for the Tax Authority to assess the transfer pricing risk of the enterprise.
See details: Declare related party transactions on HTKK
Components of the Transfer Pricing Documentation
The transfer pricing documentation is legal evidence proving that the related transactions of an enterprise are carried out according to the independent market principle. This documentation includes 03 levels.
| File | Condition | Content |
| Local File | Required for all businesses with related transactions. | Information about business, industry, business strategy. Describe in detail each related transaction that occurs. Functional analysis (FAR) of the enterprise and its related parties. Analysis, comparison and selection of methods for determining transfer pricing. Calculate price adjustments (if necessary). |
| Master File | Applicable to businesses that are members of multinational corporations. The Group's global consolidated revenue is over VND 10,000 billion. | Overview of the Group's ownership structure. Global business operations. The Group's general transfer pricing policy. |
| Country-Based Profit and Loss Report (CbCR) | Applicable to multinational corporations with total global consolidated revenue of over VND 18,000 billion. | Summary information on revenue distribution. Profit, tax paid in each country. Business activities between countries. |
The three levels of related party transaction records above show the increasing level of transparency that enterprises must meet when participating in multinational corporations. In particular, Local File is a mandatory obligation for most enterprises with related party transactions, while Master File and CbCR only apply when the Group's consolidated revenue reaches the threshold according to Decree 132. The full and timely preparation of these Records not only helps enterprises comply with the law but also reduces the risk of tax collection, tax assessment and increases transparency in operations.
Cases exempted from preparing price determination dossiers
Decree 132/2020/ND-CP provides specific conditions for businesses to be exempt from preparing Price Determination Documents, helping to reduce the compliance burden for small businesses or those with low transfer pricing risks.
Businesses are exempt if they meet one of the following conditions:
Conditions regarding Transaction Size and Value
Both conditions must be met simultaneously:
- Total revenue generated during the tax period is less than 50 billion VND;
- Total value of all related transactions arising in the tax period is under 30 billion VND.
Conditions for the Validity of Advance Pricing Agreements (APAs)
The Enterprise has signed an Advance Pricing Agreement (APA) and continues to comply with this Agreement.
Conditions regarding profit margin and simple function execution.
- Firstly, the business only conducts transactions with related parties that are subject to corporate income tax in Vietnam;
- Second, apply the same corporate income tax rate as the related party (i.e. there is no difference in tax rates);
- Thirdly, neither of the affiliated parties is entitled to corporate income tax incentives during the tax period;
- Fourth, total revenue generated during the tax period is less than 200 billion VND;
- Fifth, apply the net profit margin before interest and corporate income tax on net revenue, after deducting interest expenses and non-deductible expenses as prescribed for distribution from 5% or more, for production from 10% or more and for processing from 15% or more.
Even if exempted from preparing a Profile, the enterprise must still:
- Declare all information regarding related-party transactions in Form 01 (Appendix on related-party transactions attached to the Corporate Income Tax Return).
- Compliance with the arm's length principle is required (prices must be within market price range).
- Pay special attention to the interest expense limit.
Interest expense and EBITDA limit
This is one of the most prominent and controversial points of the regulations on related-party transactions in Decree 132/2020/ND-CP:
- Limiting principle: The total interest expense deductible when determining corporate income tax (after deducting interest on deposits and loans) must not exceed 30% of the total net profit from business operations (EBITDA) generated during the period.
See also: How to calculate interest expense according to Decree 132.
Important new points:
- Allows the carry-forward of non-deductible interest expense (the portion exceeding 30% EBITDA) to subsequent tax periods, for a maximum of 5 years.
- The portion of interest expense exceeding the 30% EBITDA limit that is not deductible will be reduced if the business has related-party transactions that are exempt from preparing valuation reports, or only involves related-party borrowing or lending transactions.
Frequently Asked Questions about Related-Party Transactions under Decree 132
Declaration is mandatory. Even if a business only engages in loan transactions with related parties, it must still declare Appendix I, track interest expense limits, and demonstrate that the interest rate is consistent with the arm's-length principle.
The portion of interest expense exceeding the 30% EBITDA limit is not deductible for the current period but can be carried forward for up to five consecutive years if conditions are met. Businesses with a high proportion of internal borrowings should pay particular attention to this regulation to avoid tax arrears.
An APA (Advance Pricing Agreement) is a pre-agreed method for determining the taxable price between a business and the tax authority. This method helps reduce audit risks, increase certainty regarding tax policy, and limit disputes with the tax authority.
Businesses need to retain records of transfer pricing for transactions within the timeframes stipulated by current accounting and tax regulations. Businesses should keep complete records of comparative data, contracts, payment documents, internal service records, and transfer pricing policies. All of this will protect the business when explaining matters to the tax authorities.If a business only borrows from its parent company, is it required to declare related-party transactions?
How are interest expenses regulated under Decree 132?
What is an APA agreement in related-party transactions?
How long must records of related-party transactions be retained?
Conclusion and recommendations
Compliance with the regulations on related-party transactions under Decree 132 is a big challenge but also an opportunity for businesses to make their financial activities transparent, strengthen their reputation and minimize legal risks.
To maintain compliance and sustainable risk control, businesses need to implement additional:
- Periodic Review: Establish a quarterly review process for the ownership structure and management to accurately identify Affiliates and eliminate omission risks.
- Transfer pricing documentation is legal evidence demonstrating that a company's related-party transactions are conducted according to independent market principles. In practice, many businesses choose to use it. related party transaction documentation service This aims to ensure the completeness of the Local File and Master File and minimize risks during tax audits.
- Separating Interest Expense: Track net interest expense and monthly EBITDA separately to manage the 30% limit and proactively balance funding.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
Content production by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam auditors with over 30 years of experience in accounting, auditing, and financial consulting.