


Handling interest expense on deposits that exceed the 30% EBITDA threshold is the issue that causes the most confusion for many chief accountants when Decree 255/2026/ND-CP Officially effective from July 1, 2026, and applicable from the 2026 corporate income tax period. A single incorrect offsetting operation between interest on deposits, interest on loans, and interest expense can cause disallowed expenses to increase by billions of dong, resulting in back taxes and late payment penalties. This article systematically reviews the legal basis, formulas, six-step process, and common mistakes, helping businesses with related-party transactions proactively prepare for the tax settlement period.
Why is handling interest income exceeding the 30% EBITDA threshold a hot topic for the 2026 tax year?
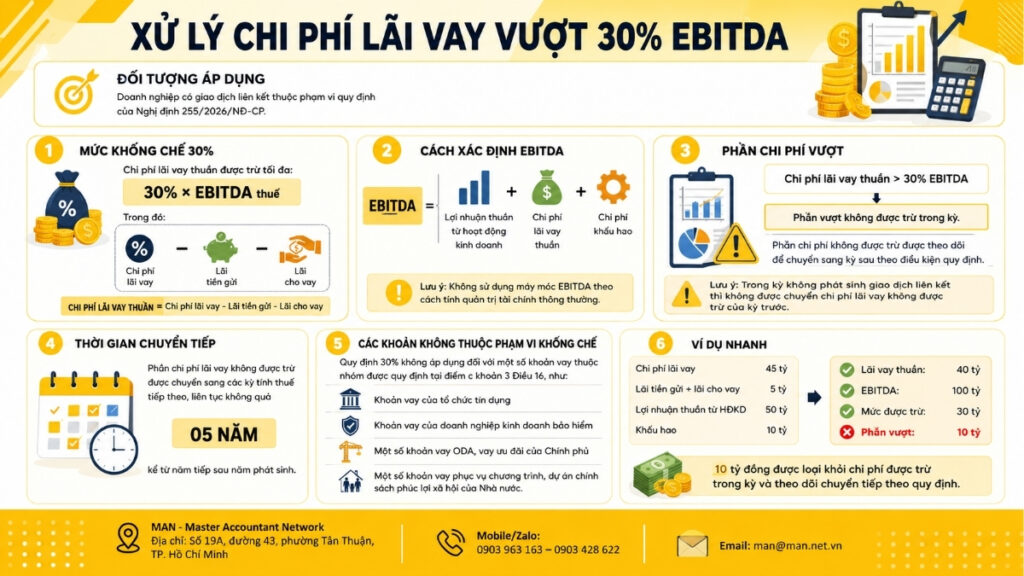
Handling interest expense exceeding the 30% EBITDA threshold involves determining the portion of net interest expense (interest expense after deducting interest on deposits and loans incurred during the period) that exceeds the 30% EBITDA taxable amount, excluding that excess from deductible expenses when calculating corporate income tax, and tracking it for carry-forward to subsequent tax periods for a period not exceeding 5 years.
Decree 255/2026/ND-CP replaces the old legal framework from July 1, 2026.
Decree 255/2026/ND-CP on tax management for enterprises with related-party transactions was issued by the Government on June 30, 2026, and takes effect from July 1, 2026, applying from the corporate income tax period of 2026. This Decree replaces Decree 132/2020/ND-CP and Decree 20/2025/ND-CP.
Points to emphasize: The 30% EBITDA threshold remains unchanged. However, the context surrounding it has changed significantly, as has the way it is identified. affiliated relationship Further clarifications have been made (including relationships arising from borrowing and lending), the threshold for exemption from reporting transfer pricing has been raised, the priority order of comparative data sources has been clearly defined, and the threshold for submitting Country-by-Country Reports has been changed to the standard of 750 million EUR in accordance with OECD practice.
Direct consequence: The group of businesses required to address interest payments on loans exceeding the 30% EBITDA threshold in 2026 may be broader than that specified in Decree 132/2020/NĐ-CP.
Three financial consequences when a business ignores the 30% EBITDA threshold.
- Firstly, corporate income tax was collected retrospectively. The portion of interest expense exceeding the threshold was disallowed, resulting in an increase in taxable income.
- Secondly, late payment penalties accumulate. The amount due is subject to late payment interest from the time it was supposed to be paid.
- Third, loss of carryforward rights. This is the most significant but insidious loss. If a business does not track excess amounts in its books and disclosures, proving carryforward rights in subsequent periods becomes almost impossible.
Legal basis for handling interest payments exceeding the 30% EBITDA threshold.
All provisions regarding the treatment of interest expenses on deposits exceeding the 30% EBITDA threshold are set forth in Clause 3 of Article 16 of Decree 255/2026/NĐ-CP, which addresses the determination of expenses for tax purposes for enterprises engaged in related-party transactions. The chief accountant must be familiar with points a, b, and c of this clause.
Point a, Clause 3, Article 16:
The total interest expense after deducting interest on deposits and loans incurred during the period of the taxpayer is deductible when determining taxable income for corporate income tax purposes, provided it does not exceed 30% of the total net profit from business operations during the period plus interest expense after deducting interest on deposits and loans incurred during the period plus depreciation expense incurred during the period of the taxpayer.
Three details determine the entire calculation result:
- After deducting interest on deposits and interest on loans, the controlled item is net interest expense, not gross interest expense. This is precisely why the process of addressing interest income from deposits that exceeds the 30% EBITDA threshold must always begin with the separation of financial revenue.
- Total net profit from business operations during the period, taken from the net profit from business operations figure in the Income Statement, not profit before tax.
- After deducting interest on deposits and loans, once on the controlled side and once on the added side of the denominator, the second deduction is the most common technical error, inflating EBITDA and creating a false sense of security.
Point b, Clause 3, Article 16:
The portion of interest expense not deductible under point (a) of this clause shall be carried forward to the next tax period when determining the total deductible interest expense, provided that the total deductible interest expense incurred in the next tax period is lower than the amount stipulated in point (a) of this clause. The carry-forward period for interest expense shall not exceed 5 years from the year following the year in which the non-deductible interest expense was incurred.
Point c, Clause 3, Article 16:
The limitation stipulated in point a does not apply to loans of taxpayers that are credit institutions under the Law on Credit Institutions; insurance business organizations under the Law on Insurance Business; official development assistance (ODA) loans, preferential loans of the Government implemented through the method of the Government borrowing from foreign countries to lend to enterprises; loans for implementing national target programs; and loans for investment in programs and projects implementing the State's social welfare policies.
Note: This is an exception based on the entity and source of funds, not an exception based on the will of the business. A commercial enterprise borrowing from a bank is still subject to the handling of interest payments exceeding the 30% EBITDA threshold if that loan gives rise to an affiliated relationship as per Article 5.
Understand these three components before processing interest-bearing deposits that exceed the 30% EBITDA threshold
The standard formula for handling interest payments exceeding the 30% EBITDA threshold can be summarized as follows:
Determine net interest expense:
Net interest expense = Interest expense incurred during the period – (Interest on deposits + Interest expense on loans incurred during the period) |
Determine EBITDA:
EBITDA = Net profit from business operations + Net interest expense + Depreciation expense |
Then, the threshold is excluded:
Deduction threshold = 30% x EBITDA |
The overtaken section was eliminated:
Excess amount disallowed = Net interest expense – Deduction threshold |
How are interest on deposits and interest on loans offset?
Specifically:
- Only offset amounts arising during the period: Accrued interest from the previous period or interest received in advance for the next period must be adjusted to the correct period.
- The true nature of the revenue is that interest on bank deposits and interest from lending activities are offset. Other items included in financial income such as exchange rate differences, dividends, foreign currency gains, and payment discounts are not subject to offsetting.
- No arbitrary offsetting: If interest income from deposits and loans exceeds interest expense, resulting in a negative net interest expense, there is no obligation to account for deposit interest income exceeding the 30% EBITDA threshold; however, the company must still report it in full.
What are the differences between tax-based EBITDA and financial-based EBITDA?
Many CFOs are accustomed to using management EBITDA (earnings before tax + interest + depreciation) and applying it directly to calculations. This approach often leads to inaccurate results for two reasons: tax EBITDA is derived from net operating profit, a figure that includes financial revenue and financial expenses but excludes other income and expenses; and the interest component should be net interest expense, not gross interest expense.
The difference in other income alone, such as profits from the liquidation of fixed assets amounting to tens of billions of dong, is enough to cause the two EBITDA figures to differ.
Reference: Formula for calculating deductible interest expense.
Procedure for Handling Interest Income Exceeding the 30% EBITDA Threshold
The procedure for handling interest income on deposits exceeding the 30% EBITDA threshold is as follows:
- Step 1 – Determining eligibility: Review the ownership structure, loan agreements, guarantee letters, and borrowing/lending transactions with the managing individual to determine whether the business falls within the scope of Article 5. The conclusion must be documented in writing with supporting evidence.
- Step 2 – Financial Data Separation: Prepare a detailed table of interest expense for each loan agreement, separating interest on deposits and interest on loans, comparing it with the general ledger accounts 515 and 635, and excluding the portion of interest expense that has been capitalized into work-in-progress assets.
- Step 3 – Calculate taxable EBITDA and the 30% threshold: Apply the correct formula as specified in point a, clause 3, Article 16, and save the calculation sheet with references to each item on the audited financial statements.
- Step 4 – Identify and exclude the excess: Record the portion of interest expense that is not deductible from the upward adjustment of taxable income on the corporate income tax return.
- Step 5 – Open the carry-over tracking ledger: Create a separate tracking table for each year of occurrence, clearly recording the amount, year of occurrence, year of carry-over expiration, and the amount used in each period. This is crucial documentation for subsequent periods.
- Step 6 – Completing the documentation and declaration: Declare the interest expense ratio according to the Appendix issued with the Decree, submit it along with the tax return, and simultaneously complete the Transfer Pricing Documentation if it is not exempt from preparation.
Real-world example: Handling interest-bearing deposits exceeding the 30% EBITDA threshold at a manufacturing company
Suppose: Company A (manufacturer of components, borrowing from its parent company abroad) has the following data for the 2026 tax period:
| Indicators | Amount (billion VND) |
| Net operating profit | 50 |
| Interest expense incurred during the period | 45 |
| Interest earned on deposits + Interest earned on loans during the period | 5 |
| Depreciation expense for the period | 10 |
Calculation steps:
- Net interest expense = 45 − 5 = 40 billion VND
- Taxable EBITDA = 50 + 40 + 10 = 100 billion VND
- Deduction threshold = 30% × 100 = 30 billion VND
- Excess amount rejected = 40 - 30 = 10 billion VND
Company A adjusts its taxable income upwards by VND 10 billion in the 2026 period, and simultaneously records this VND 10 billion in the carry-forward ledger, with a continuous use period not exceeding 5 years from 2027.
Assuming that in 2027 the company reduces its outstanding debt, with net interest expense at 20 billion VND while the 30% EBITDA threshold reaches 28 billion VND, there is a remaining margin of 8 billion VND. The company is allowed to carry forward 8 billion VND from the outstanding balance of 2026 to be deducted in 2027; the remaining 2 billion VND will continue to be monitored for subsequent periods within the remaining term.
This figure illustrates why addressing interest expense on deposits that exceeds the 30% EBITDA threshold should be viewed as a multi-year plan, rather than a one-time adjustment.
Important Note: If no related-party transactions occur during the period, the non-deductible interest expense from the previous period cannot be carried forward.
For example: If, in 2025, there are excess interest expenses but no related-party transactions occur in 2026, the enterprise is not allowed to carry forward the excess amount from 2025 to 2026.
Special circumstances: Negative EBITDA or interest income from deposits exceeding interest expense.
If EBITDA is negative or zero, the deduction threshold is zero or meaningless, resulting in the entire net interest expense being disallowed for the period. Businesses that are losing money, have made significant investments, or are newly operational often find themselves in this situation and are the group requiring the most rigorous transitional tracking.
Net interest expense is considered negative when interest income from deposits plus interest on loans exceeds interest expense, provided there is no excess. Businesses should still declare interest as usual and keep the spreadsheet for explanation.
Note: If EBITDA is less than 0, the entire interest expense for the tax period is not deductible. The non-deductible portion of interest expense is carried forward to subsequent tax periods.
Documents and disclosures demonstrating the treatment of interest-bearing deposits exceeding the 30% EBITDA threshold
The method of calculation must be proven during an audit. The minimum required documentation should include:
- The 30% EBITDA threshold spreadsheet includes references to financial statement figures and accounting account numbers.
- A detailed breakdown of interest expenses for each loan agreement, including the loan contract, appendices, payment documents, and bank confirmation of interest.
- The statement of deposit and loan interest is compared with the bank statement.
- The multi-year transitional tracking table shows the opening balance, transactions, usage, closing balance, and expiration year.
- The appendix declaring the interest expense ratio, using the form issued with Decree 255/2026/ND-CP, must be submitted together with the corporate income tax return.
- The documentation for determining transfer pricing (Country Documentation, Global Documentation, Country-by-Country Report) should pay particular attention to the section demonstrating that the interest rate on loans to related parties is consistent with the arm's-length principle.
Related-party transactions always require expertise due to the complexity of the operations, as well as a thorough understanding of tax law and finance. If a business does not have a dedicated department, consulting with a professional is recommended. related party transaction advisory services For in-depth support, consult specialized and experienced organizations like MAN – Master Accountant Network.
With over 30 years of experience in the field and having partnered with more than 500 FDI enterprises, MAN is confident in supporting businesses in all matters related to related-party transactions (transfer pricing).
A note on the nature of it: If the interest rate on related-party loans does not reflect market prices, the tax authorities may reassess the interest expense before applying the 30% EBITDA threshold. This means that a weak related-party transaction pricing record will cause the amount exceeding the threshold to be inflated significantly.
Conclude
If your company's interest expense record still has uncertainties, from determining the eligibility of related parties and separating interest income from deposits to tracking multi-year carry-over statements, let the team of related party transaction experts at MAN – Master Accountant Network help your business prepare for the upcoming tax year.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network. He is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions Regarding the Treatment of Interest Income Exceeding the 30% EBITDA Threshold
Do businesses with no related-party transactions have to treat interest income exceeding the 30% EBITDA threshold?
No. The limitation stipulated in point a, clause 3, Article 16 only applies to taxpayers with related-party relationships and related-party transactions occurring during the period. However, businesses should still keep records proving they do not fall under the scope of Article 5.
Are any interest expenses that exceed the limit permanently lost?
It is not lost immediately. According to point b, clause 3, Article 16, the non-deductible portion is carried forward to the next tax period when the total deductible interest expense for that period is lower than the threshold, with the carry-forward period not exceeding 5 years from the year following the year of occurrence.
Can exchange rate gains be deducted when calculating net interest expense?
No. Only interest on deposits and interest on loans arising during the period are offset in accordance with the wording of point a, clause 3, Article 16.
Does borrowing from commercial banks give rise to an obligation to process interest payments exceeding the 30% EBITDA threshold?
It depends on the case. If the lending institution does not participate in the management, control, capital contribution, or investment in the borrowing or guaranteeing enterprise, then that loan alone does not create an affiliated relationship. Conversely, when the loan simultaneously reaches the threshold of 25% of owner's equity and over 50% of the total value of medium and long-term debts in the context of other affiliated factors, the enterprise falls within the scope of application.
If no related-party transactions occur in a tax period, is it possible to carry forward non-deductible interest expense from the previous period?
No. The carryforward under point b, clause 3, Article 16 only applies to determining the total deductible interest expense, and only to taxpayers who have related-party transactions during the period. In periods without related-party transactions, the enterprise is not within the scope of application and cannot include the outstanding balance from the previous period for deduction.