


The CbCR (Country of Births and Credit Information Exchange) mechanism has officially transitioned from an international commitment to a fully operational state in Vietnam, a change that reverses how thousands of FDI businesses determine their reporting obligations. Since the Tax Department announced the list of countries and territories that have established effective Country-by-Country Profit and Loss Reporting (CBCR) relationships with Vietnam, submitting paper reports within the scope of these exchanges is no longer accepted, while a smaller but mandatory obligation is often overlooked. This article reviews the legal basis, operation, three groups of obligations, the five-step process, and common misconceptions, helping businesses correctly identify their position before the 2026 reporting period.
Why is the CbCR automatic information exchange mechanism the biggest change in 2026?
The CbCR (Country of Births and Returns) automatic information exchange mechanism is a method whereby the Vietnamese tax authority receives the Country of Births Report of a multinational corporation directly from the foreign tax authority, through an Agreement between the competent authorities, instead of requiring the member company in Vietnam to submit the report itself.
From the outside, this is a technical shift in the flow of data. From the chief accountant's desk, it's a shift in the entire compliance focus. That shift occurred in the very year the legal framework for related-party transactions was completely rewritten. Decree 255/2026/ND-CP The regulation dated June 30, 2026, takes effect from July 1, 2026, and applies from the corporate income tax period of 2026, replacing Decree 132/2020/ND-CP and Decree 20/2025/ND-CP. Businesses must therefore update both the mechanism and the number of the cited clauses in their explanatory documents.
From BEPS Action 13 to CbC MCAA
The Country-by-Country Report (CbCR) is a product of Minimum Standard Action 13 of the OECD's Base Erosion and Profit Shifting (BEPS) Programme. The report provides a picture of the allocation of revenue, profits, taxes paid, number of employees, and tangible assets of a corporation in each country—data that no single tax authority can collect on its own.
To enable these reports to circulate between countries, the OECD designed the Multilateral Agreement between Competent Authorities on the Exchange of Earnings Reports, abbreviated as CbC MCAA.
During the implementation of Minimum Standard Action 13, Vietnam joined the CbC MCAA and, as of January 3, 2025, completed the notification procedures as stipulated in the Agreement to establish a country-by-country exchange of Profit Reporting with partner countries and territories.
Here, a distinction that professionals must understand is that signing the MCAA and activating the exchange relationship are two completely different things. Signing only creates a general legal framework between the participating parties. The exchange relationship only takes effect between Vietnam and each specific partner after both parties complete the notification procedures and meet the conditions of the Agreement, including security and technical infrastructure requirements. Therefore, the CbCR automatic information exchange mechanism does not cover the entire world; the mechanism only targets the list of activated partners, and that list changes over time.
7 countries, territories, and turning points in Official Document 3870/CT-CS
On June 10, 2026, the Tax Department issued... Official document No. 3870/CT-CS This document is sent to the Tax Departments of provinces and cities, the E-commerce Tax Office, and the Large Enterprise Tax Office, providing guidance on fulfilling obligations related to the Country-by-Country Profit Reporting. The document also informs that Vietnam has established effective exchange relations with 37 countries and territories, as listed in the attached Appendix.
This list covers almost all major sources of FDI into Vietnam: South Korea, Japan, Singapore, China, the Netherlands, the United Kingdom, Germany, France, Australia, India, Sweden, Switzerland, and many other countries and territories. In other words, the majority of FDI enterprises in Vietnam have been included in the CbCR automatic information exchange mechanism since this reporting period.
The most practical content lies in the guidance section: for taxpayers in Vietnam whose parent company is located abroad, they must submit a Country-by-Country Report in accordance with the regulations of the country of residence and within the scope of exchanges under the CbC MCAA with the countries and territories mentioned in the Official Letter. The tax authorities will receive the Country-by-Country Report through the automatic information exchange mechanism under international tax agreements to which Vietnam is a member, and will not accept Country-by-Country Reports submitted by taxpayers in paper form or other forms.
Legal basis of the CbCR automatic information exchange mechanism.
The current legal framework comprises three layers:
- International Commitments (CbC MCAA);
- Domestic regulations are based on Decree 255/2026/ND-CP (considered under Law on Tax Administration No. 108/2025/QH15).;
- And the implementation document from the tax authority according to Official Letter 3870/CT-CS, along with periodic announcements on the tax authority's website.
Official document 3870/CT-CS, issued on June 10, 2026, which is before the new Decree was signed, cites the provisions in the draft Decree amending and supplementing Decree No. 132/2020/ND-CP, specifically point d, clause 5, Article 18 of the draft:
In cases where taxpayers have a parent company located abroad that is required to submit a Country-by-Country Report of Profits as stipulated by the country of residence, the tax authorities will automatically exchange information in accordance with commitments under Vietnam's international tax agreements.
Agreement of the competent authorities
The entire CbCR automatic information exchange mechanism revolves around a concept defined in Clause 3, Article 4 of Decree 255/2026/ND-CP:
Agreement of Competent Authorities is a shortened term for an agreement concluded between the competent authorities of Vietnam and a partner country or territory on the basis of an international treaty or international agreement that provides for the exchange of information, specifically stipulating the automatic exchange of Country-by-Country Profit Reports.
Note: Without an existing agreement in effect with the country where the ultimate parent company resides, there is no automatic information exchange mechanism (CbCR) for that case, and the obligation to submit reports immediately reverts to the business in Vietnam.
When are businesses not required to submit CbCR in Vietnam?
Article 19 of Decree 255/2026/ND-CP stipulates the responsibilities of taxpayers related to the Country-by-Country Profit Reporting, setting a common threshold of consolidated global revenue in the fiscal year immediately preceding the reporting year equivalent to 750 million Euros or more.
For businesses in Vietnam with a parent company located abroad, the first exemption from payment falls under point a.1, clause 2:
The ultimate parent company is obligated to prepare and submit a Country-by-Country Report of Profits in the country or territory where it resides, and this report is automatically exchanged with the Vietnamese tax authorities in accordance with the Agreement of the competent authorities;
Taxpayers in Vietnam shall submit a Notice of Entity to be Submitted to the Vietnamese tax authorities as prescribed in point d of this clause.
The second exemption, as stated in point a.2, applies when the ultimate parent company designates an organization to submit the Country-by-Country Report on its behalf in the country or territory where the organization is located, no later than the end of the ultimate parent company's financial year, and simultaneously meets five conditions:
- The host country has regulations requiring the submission of reports;
- That country has a valid Agreement of a competent authority with Vietnam at the time the submission deadline is due;
- That country does not fall under the category of countries that do not systematically exchange information;
- The organization acting on behalf of the client has notified the local authorities if required by the laws of that country;
- And taxpayers in Vietnam send the Notification along with the designation document.
See also: New points in Decree 255/2026/ND-CP regarding related-party transactions.
Tax authorities' obligations regarding confidentiality and transparency.
Clause 7 of Article 21 of Decree 255/2026/ND-CP is binding on the tax authorities:
Tax authorities implementing the automatic information exchange mechanism must maintain the confidentiality of information in accordance with international treaties and agreements on taxation to which Vietnam is a signatory or a party, and according to the standards of the Global Forum on Transparency and Exchange of Information for Tax Purposes. Annually, the tax authorities publish a list of foreign tax authorities that automatically exchange information regarding the Country-by-Country Report and any instances of non-systematic information exchange (if any) on the tax authority's website.
Furthermore, the Decree adds a very noteworthy principle: The requirement to submit the Country-by-Country Report in Vietnam under point b, clause 2, Article 19 shall only be implemented when Vietnam meets the conditions regarding information confidentiality, consistency, and proper use of information as stipulated in point h, clause 2, Article 30 of the Law on Tax Administration No. 108/2025/QH15; the tax authority is responsible for publicly disclosing the fulfillment of these conditions on the tax authority's website.
How does the CbCR automatic information exchange mechanism operate in practice?
The data flow follows three stages:
- Stage 1: The ultimate parent company submits the Country-by-Country Report of Profits to the tax authority of its country of residence, in accordance with the laws of that country.
- Stage 2: The tax authority of that country transmits the report to the Vietnamese tax authority in accordance with the Agreement of the competent authorities, in the standard OECD format.
- Stage 3: The Vietnamese tax authorities receive and integrate the data into the risk management system.
Key points to note: Businesses in Vietnam are not part of the data transmission network. Their sole role in the CbCR (Country of Births and Returns) automated information exchange mechanism is to identify to the tax authorities where their company's reports will originate, who will submit them, and in which country. This is the function of the Notification of the Country of Births and Returns Filed.
Conditions for a valid exchange relationship
Based on the regulations mentioned above, three conditions must be met simultaneously:
- The ultimate parent company is obligated to prepare and submit reports in its country of residence: If the laws of that country do not impose this obligation, the mechanism has nothing to offer, and the enterprise falls under the case of point b.1, paragraph 2, Article 19.
- There exists an agreement with a competent authority in effect with Vietnam at the time the report is due: Note that the reference point is the due date, not the date the company submits the report or the end of the fiscal year.
- The exchange relationship does not fall into a state where information is not exchanged systematically.
The situation of not exchanging information systematically.
Based on Clause 13, Article 4 of Decree 255/2026/ND-CP:
The situation of not systematically exchanging information refers to a situation where a country or territory has an existing automatic exchange agreement for Country-by-Country Profit Reports, but temporarily suspends the exchange for reasons inconsistent with the terms of that agreement, or consistently fails to exchange the Country-by-Country Profit Reports it holds, resulting in the Vietnamese tax authorities not receiving the required reports.
The exchange of information remains valid on paper, but the actual data doesn't arrive. Businesses are required to file reports in Vietnam, but only after this situation has been communicated to taxpayers in Vietnam.
Differences in revenue thresholds between countries.
Enterprises are not required to submit a Country-by-Country Report under Clause b, Paragraph 2, Article 19 in cases where the ultimate parent company is not obligated to prepare and submit the report in its country of residence because the group's consolidated global revenue, as shown in the consolidated financial statements of the fiscal year immediately preceding the reporting year, is lower than the threshold required by that country or territory, due to differences in revenue thresholds, currencies, or principles for determining revenue between countries.
This is a practical solution for corporations close to the €750 million threshold. Different exchange rates can cause a corporation to exceed the threshold according to Vietnamese calculations but fall below it according to the calculation method of its parent company. Such cases require careful justification and documentation, including consolidated financial statements and the basis for the conversion.
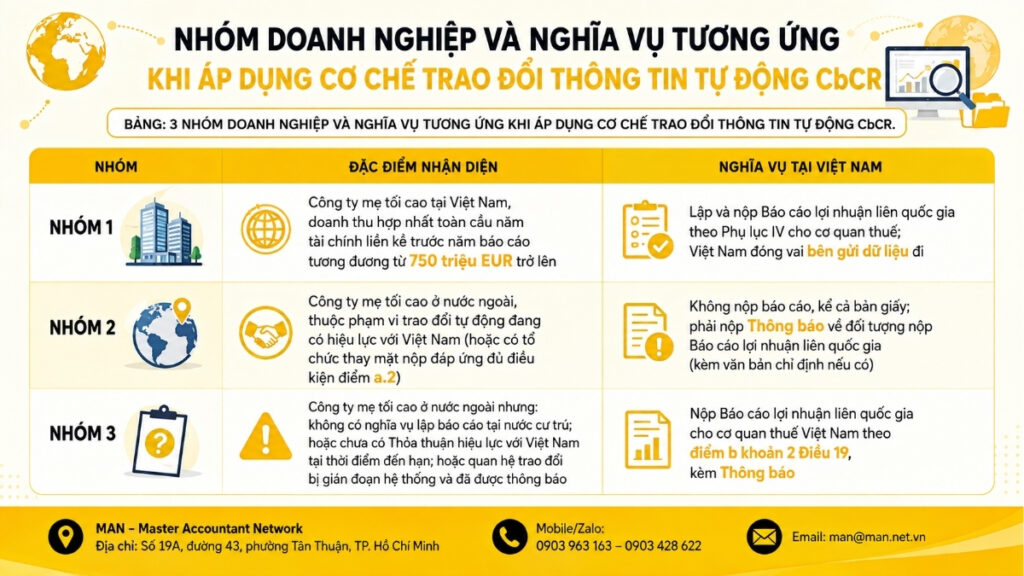
Business groups and corresponding obligations when applying the CbCR automatic information exchange mechanism.
Below is a summary of the business groups and their corresponding obligations when applying the mechanism.
| Group | Identifying characteristics | Obligations in Vietnam |
| Group 1 | The ultimate parent company in Vietnam has consolidated global revenue of €750 million or more in the fiscal year immediately preceding the reporting year. | Prepare and submit the Country-by-Country Report of Profits under Annex IV to the tax authorities; Vietnam acts as the data sender. |
| Group 2 | The ultimate parent company is located overseas and falls within the scope of the automatic trading system currently in effect with Vietnam (or has an organization submitting on its behalf that meets the conditions in point a.2). | Failure to submit reports, including paper copies, is prohibited; instead, a Notice of Entity to File the Country-by-Country Report (with designation letter if applicable) must be submitted. |
| Group 3 | The ultimate parent company is located overseas but: has no reporting obligations in its country of residence; or does not have a valid agreement with Vietnam at the time of its expiration; or the exchange relationship has been systematically interrupted and has been notified. | Submit the Country-by-Country Report to the Vietnamese tax authorities in accordance with point b, clause 2, Article 19, along with the Notification. |
Please note the procedures and deadlines for submitting the report:
- The report was submitted in encrypted XML format;
- Notifications and reports are submitted through the Tax Management Information System;
- The deadline for submitting the Report is no later than 12 months from the end of the fiscal year of the ultimate parent company for the reporting year.
Regarding the notification on the entities required to submit the Country-by-Country Report (Form No. 01/TB-BCLN):
- From July 1st, 2026, when Decree 255 officially takes effect, taxpayers only need to submit the Notification. once When the obligation first arises, the deadline is no later than the end of the fiscal year of the ultimate parent company of the reporting year. When there are changes to the information in the most recently submitted Notice, including cases of termination of the obligation, the enterprise must submit an updated Notice no later than the deadline. 90 days since the date the change occurred.
- In cases where a corporation has more than one taxpayer in Vietnam and the ultimate parent company abroad designates a taxpayer in Vietnam to submit the Notice, the designated taxpayer is obligated to submit the Notice along with the designation document.
Reference: Limitations on the use of CbCR reports.
What changes has Decree 255/2026/ND-CP brought compared to Decree 132/2020/ND-CP on CbCR?
Decree 255/2026/ND-CP inherits and replaces Decree 132/2020/ND-CP. Specifically, what changes does Decree 255 bring compared to the old regulations? Let's take a look at the following table with MAN – Master Accountant Network:
| Content | Decree 132/2020 | Decree 255/2026 |
| Global consolidated revenue threshold | Determined in VND (18,000 billion VND or more) | This is equivalent to 750 million EUR, converted using the exchange rate published by the State Bank of Vietnam. |
| Threshold determination period | Based on revenue during the tax period | According to the fiscal year immediately preceding the reporting year. |
| Notification regarding the reporting entities | Submit annually | Submit once, and update within 90 days if changes occur. |
| Format | There are no clear regulations yet. | The XML file has been encrypted and submitted through the Tax Management Information System. |
| Conditions for requesting a CbCR in Vietnam | Not yet set | Vietnam must meet the conditions of confidentiality, consistency, proper use, and transparency of compliance. |
| Differences in thresholds between countries. | Not yet processed | Recorded as a case where no payment is required. |
List of countries with activated CbCR exchange relationships
The table below shows the activated bilateral exchange relationships currently in effect for the automatic CbCR exchange mechanism between tax authorities under the MCAA CbC Agreement. This table also includes relationships based on EU law, as well as bilateral agreements on CbC exchange under tax agreements or tax information exchange arrangements, to the extent notified to the OECD Secretariat.
| No. | From country/region | To the country/territory | Legal Note |
| 1 | Vietnam | Australia | CBC MCAA has been activated. |
| 2 | Vietnam | Shirt | CBC MCAA has been activated. |
| 3 | Vietnam | Belgium | CBC MCAA has been activated. |
| 4 | Vietnam | Bulgaria | CBC MCAA has been activated. |
| 5 | Vietnam | China | CBC MCAA has been activated. |
| 6 | Vietnam | Croatia | CBC MCAA has been activated, effective for tax periods beginning January 1, 2024. |
| 7 | Vietnam | Czech Republic | CBC MCAA has been activated. |
| 8 | Vietnam | Denmark | CBC MCAA has been activated. |
| 9 | Vietnam | Estonia | CBC MCAA has been activated. |
| 10 | Vietnam | France | CBC MCAA has been activated. |
| 11 | Vietnam | Virtue | CBC MCAA has been activated. |
| 12 | Vietnam | Greece | CBC MCAA has been activated. |
| 13 | Vietnam | Hong Kong | CBC MCAA has been activated, effective for tax periods beginning January 1, 2024. |
| 14 | Vietnam | Iceland | CBC MCAA has been activated. |
| 15 | Vietnam | India | CBC MCAA has been activated. |
| 16 | Vietnam | Ireland | CBC MCAA has been activated. |
| 17 | Vietnam | Ý | CBC MCAA has been activated. |
| 18 | Vietnam | Japan | CBC MCAA has been activated. |
| 19 | Vietnam | Korea | CBC MCAA has been activated. |
| 20 | Vietnam | Japanese | CBC MCAA has been activated, effective for tax periods beginning January 1, 2024. |
| 21 | Vietnam | Luxembourg | CBC MCAA has been activated. |
| 22 | Vietnam | Malaysia | CBC MCAA has been activated. |
| 23 | Vietnam | Malta | CBC MCAA has been activated. |
| 24 | Vietnam | Netherlands | CBC MCAA has been activated. |
| 25 | Vietnam | Norway | CBC MCAA has been activated. |
| 26 | Vietnam | Peru | CBC MCAA has been activated. |
| 27 | Vietnam | Poland | CBC MCAA has been activated. |
| 28 | Vietnam | Portugal | CBC MCAA has been activated. |
| 29 | Vietnam | Russian Federation | CBC MCAA has been activated. |
| 30 | Vietnam | Singapore | CBC MCAA has been activated. |
| 31 | Vietnam | Slovakia | CBC MCAA has been activated. |
| 32 | Vietnam | Slovenia | CBC MCAA has been activated. |
| 33 | Vietnam | Spain | CBC MCAA has been activated. |
| 34 | Vietnam | Sweden | CBC MCAA has been activated. |
| 35 | Vietnam | Switzerland | CBC MCAA has been activated. |
| 36 | Vietnam | Thailand | CBC MCAA has been activated. |
| 37 | Vietnam | United Kingdom | CBC MCAA has been activated. |
Conclude
The CbCR automatic information exchange mechanism has completed its journey from international commitment to practical operation: Vietnam joined the CbC MCAA and completed the notification procedures on January 3, 2025, establishing effective exchange relationships with 37 countries and territories according to Official Letter 3870/CT-CS dated June 10, 2026, and has a complete domestic legal framework in Articles 19 and 21 of Decree 255/2026/ND-CP applicable from the corporate income tax period of 2026.
If your company is still unsure which of the three groups above it belongs to, or wants to cross-check your group's CbCR data with related-party transaction records in Vietnam before the tax authorities do so, let the experts at MAN – Master Accountant Network accompany your company.
Contact MAN – Master Accountant Network For expert support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network. He is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.