





In an increasingly complex global economic landscape, corporate financial management is not just about generating profits, but also about compliance with and optimization of tax obligations. For foreign-invested enterprises (FDI) or corporations with multiple subsidiaries, calculating deductible interest expenses is always a major challenge for accounting and finance departments.
On June 30, 2026, the Government issued Decree 255/2026/ND-CP Regulations on tax administration for related-party transactions of affiliated enterprises. The Decree takes effect on July 1, 2026, applies to the 2026 corporate income tax period, and replaces Decree No. 132/2020/ND-CP and Decree No. 20/2025/ND-CP. Decree 255 maintains the 30% EBITDA threshold while further clarifying how to identify related-party relationships and how to file tax returns. This article provides a comprehensive and accurate overview of the legal and practical aspects to help businesses confidently determine reasonable interest expenses.
Legal context regarding tax management and interest expense
From Decree 20/2017/NĐ-CP to Decree 132/2020/NĐ-CP, the tax authorities’ stance on limiting interest expense deductions has become increasingly clear and firm. The core objective is to prevent transfer pricing through interest expenses and the phenomenon of thin capitalization—where companies borrow excessively from related parties to inflate costs, thereby reducing taxable income in Vietnam.
Decree No. 255/2026/NĐ-CP was issued on the basis of Law on Tax Administration No. 108/2025/QH15 and Corporate Income Tax Law No. 67/2025/QH15. The provisions governing the limitation of interest expense are now set forth in Clause 3 of Article 16 of the Decree. As tax authorities increasingly utilize technology in risk management and cross-check data between the related-party transaction schedule and financial statements, a thorough understanding of how to calculate deductible interest expenses is no longer an option but a mandatory requirement.
The necessary conditions for interest expense to be considered valid before deduction are met.
A common mistake is that many accountants focus only on the 30% limit and forget that, before applying the limit formula, the interest expense must meet the basic conditions of the Corporate Income Tax Law. To understand how to calculate deductible interest expense, businesses need to check the following four filters:
Serving production and business activities
Loans must have a clear purpose, substantiated by a business plan or investment project. If a business borrows funds but leaves them idle in its account or lends them to related parties without earning interest, the tax authorities have the right to disallow the corresponding interest expense.
Capital contribution obligations according to schedule.
Base Clause 9, Article 10 of Decree No. 320/2025/ND-CP, Interest expense corresponding to the remaining capital shortfall according to the capital contribution schedule stipulated in the company's charter will not be included in deductible expenses. This is the first and most important step in calculating deductible interest expense. Businesses must eliminate this portion of interest expense before including the data in the 30% EBITDA control formula.
Independent interest rate controls
If borrowing from entities other than credit institutions (e.g., personal loans), the interest rate must not exceed the basic interest rate announced by the State Bank of Vietnam. Any amount exceeding this limit will certainly be excluded from deductible expenses.
See details: Is taking out a bank loan considered a related-party transaction?.
In addition, for loans from related parties, the interest rate must comply with the arm’s-length principle. Decree No. 255/2026/NĐ-CP defines “interest payments in borrowing and lending activities” as one of the cases in which the method of comparing related-party transaction prices with arm’s-length transaction prices applies (Article 13, Clause 1).
Legality of payment documents
All interest payments must be supported by a loan agreement, personal income tax withholding certificate (if borrowing from an individual), and most importantly, non-cash payment documentation for loans/principal and interest repayments of 20 million VND or more.
New Provisions in Decree 255 Regarding the Determination of Affiliated Relationships
The method for calculating deductible interest expenses under the 30% cap applies only when a business has related-party relationships and has engaged in related-party transactions during the period. Paragraph 2 of Article 5 of Decree 255/2026/NĐ-CP lists the cases in which parties are considered to have a related-party relationship. Common criteria in borrowing activities include:
- Ownership of capital: One party directly or indirectly holds at least 25% of the other party’s contributed capital.
- Loans, Guarantees: An enterprise guarantees or lends capital to another enterprise in any form (including third-party loans secured by related-party financing and similar financial transactions) provided that the total outstanding debt of the borrowing enterprise to the lending or guaranteeing enterprise is at least equal to 25% of the owner's equity of the borrowing enterprise and accounts for more than 50% of the total outstanding debt of all medium and long-term debts of the borrowing enterprise.
- Hosted by: An enterprise designates more than 50% members of the executive management board or holds control over another enterprise (subpoint d), or exercises de facto management, control, or decision-making authority over the production and business operations of that other enterprise
- Loans and borrowing from individuals: A business that borrows, lends, or lends out at least 10% of owners’ equity at the time a transaction occurs during the tax period with an individual who manages or controls the business, or with an individual with whom the business has a family relationship
Notes on Loans from Financial Institutions
The loan eligibility criteria do not apply in any of the following three cases:
- The guarantor or lender is an economic organization operating in accordance with the Law on Credit Institutions that does not, either directly or indirectly, participate in the management, control, capital contribution, or investment in the borrower or the entity for which the guarantee is provided;
- The guarantor or lender is the aforementioned economic entity, and neither party is directly or indirectly subject to the management, control, capital contribution, or investment of a third party;
- The creditor and the guarantor are state-owned organizations with 100% authorized capital that are authorized to purchase, sell, and resolve debts; they do not directly or indirectly participate in the management, control, capital contribution, or investment in the debtor enterprise or the enterprise for which the guarantee is provided.
See details: 12 methods for determining affiliated relationships under Decree 255.
Detailed instructions on how to calculate deductible interest expense (Rule 30% EBITDA)
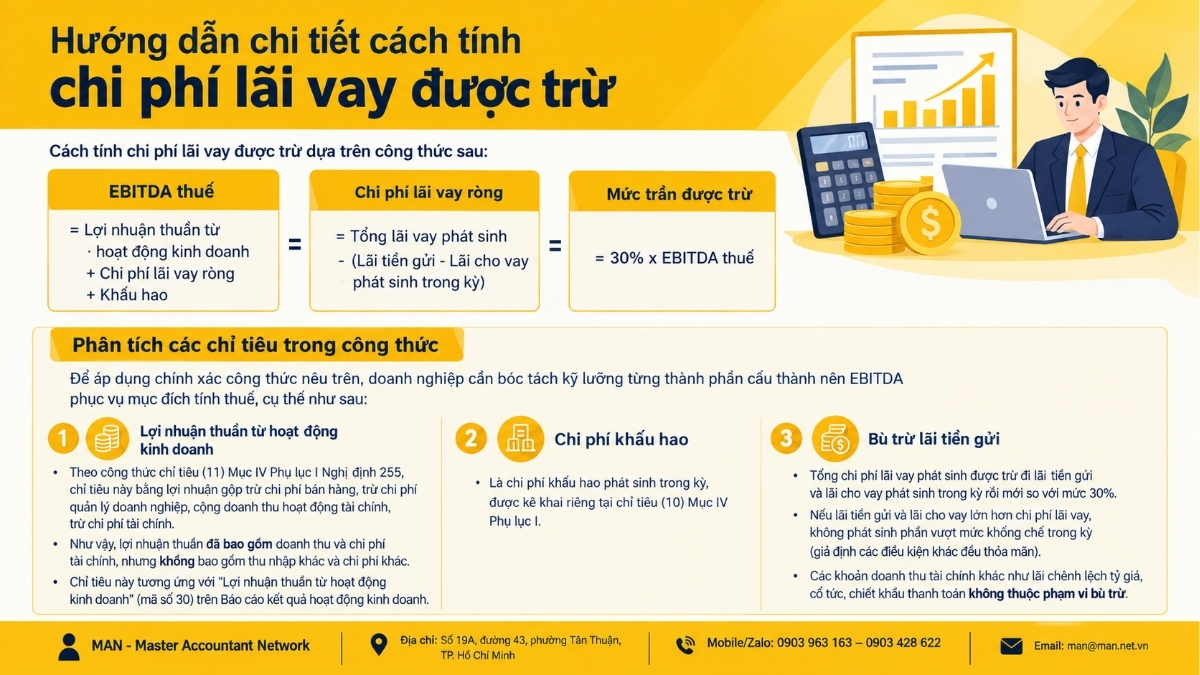
This is the key provision of Paragraph 3 of Article 16 of Decree No. 255/2026/ND-CP and requires absolute precision in calculations.
Formula for determining the ceiling
Point a, Clause 3, Article 16 of Decree 255/2026/ND-CP stipulates:
The total interest expense after deducting interest on deposits and loans incurred during the period of the taxpayer is deductible when determining taxable income for corporate income tax purposes, provided it does not exceed 30% of the total net profit from business operations during the period plus interest expense after deducting interest on deposits and loans incurred during the period plus depreciation expense incurred during the period of the taxpayer.
Specifically, the method for calculating deductible interest expense is based on the following formula:
Taxable EBITDA = Net operating profit + Net interest expense + Depreciation |
In there:
Net interest expense = Total interest expense incurred – (Interest earned on deposits – Interest income from loans incurred during the period) |
Deductible limit:
Deductible cap = 30% × taxable EBITDA |
Analyze the indicators in the formula.
To accurately apply the above formula, businesses need to carefully break down each component of EBITDA for tax purposes, specifically as follows:
- Net Profit from Business Operations: According to the formula for Indicator (11) in Section IV of Appendix I of Decree 255, this indicator is equal to gross profit minus selling expenses, minus general and administrative expenses, plus revenue from financial activities, minus financial expenses. Thus, net profit included revenue and financial expenses, but excludes Other income and other expenses. This item corresponds to “Net income from operating activities” (code 30) on the Statement of Operating Activities.
- Depreciation expense: This refers to the depreciation expense incurred during the period, which is reported separately in line item (10) of Section IV of Appendix I.
- Offset of interest income on deposits: Total interest expense incurred is reduced by interest income on deposits and interest income from loans incurred during the period before being compared to the 30% limit. If interest income from deposits and loans exceeds interest expense, no excess over the control limit arises during the period (assuming all other conditions are met). Other financial income, such as foreign exchange gains, dividends, and payment discounts Are not falls within the scope of offsetting.
The difference between Tax EBITDA and Accounting EBITDA
EBITDA used in the calculation of interest expense differs from management EBITDA in two ways:
- Operating EBITDA is typically calculated based on pre-tax profit, which already includes other income and other expenses. Tax EBITDA is derived from net operating profit. A large gain on the disposal of assets can cause a significant difference between the two figures.
- EBITDA plus interest expense net, not gross interest.
See details: EBITDA Formula and Ways to Distinguish It from EBIT.
A detailed example illustrating how to calculate deductible interest expense.
Let's analyze a real-world example of TechVina Joint Stock Company (with related-party transactions) in the 2025 financial year:
Actual data:
- Net profit from business operations: 20 billion VND.
- Interest expenses incurred from banks and the parent company: VND 12 billion.
- Interest earned on idle cash deposits: 2 billion VND.
- Asset depreciation expense: 5 billion VND.
Steps to apply the method for calculating deductible interest expense:
- Determine the net interest expense: 12 billion – 2 billion = 10 billion VND.
- Determine taxable EBITDA: 20 billion VND (Profit) + 10 billion VND (Net Interest Expense) + 5 billion VND (Depreciation) = 35 billion VND.
- Determine the interest rate ceiling (30%): 30% * 35 billion = 10.5 billion VND.
- Result: Since the net interest expense (10 billion) is less than the ceiling (10.5 billion), the entire 10 billion net interest expense is accepted as a deductible expense. The total actual deductible interest expense is 12 billion (including the portion offset by interest on deposits).
Result: Net interest expense (10 billion) is less than the cap (10.5 billion), so the entire 10 billion in net interest expense is recognized as a deductible expense. The total actual interest expense that is deductible is 12 billion (including the portion offset against interest income on deposits). The rate reported in Item (14) of Appendix I is 28.57%.
Assuming net interest expense is 15 billion and all other factors remain constant, net income would decrease accordingly to 15 billion, pre-tax EBITDA would remain at 35 billion, and the cap would remain at 10.5 billion. The company is only allowed to deduct 10.5 billion and must exclude 4.5 billion from deductible expenses when calculating corporate income tax. This 4.5 billion is reported in line (9.1.b) to track the carryover to the next period.
Clearly, understanding how deductible interest expenses are calculated helps businesses accurately estimate their tax liability.
Mechanism for carrying forward non-deductible interest expense
Point b of Paragraph 3 of Article 16 of Decree No. 255/2026/ND-CP provides as follows:
The portion of interest expense not deductible under point (a) of this clause shall be carried forward to the next tax period when determining the total deductible interest expense, provided that the total deductible interest expense incurred in the next tax period is lower than the amount stipulated in point (a) of this clause. The carry-forward period for interest expense shall not exceed 5 years from the year following the year in which the non-deductible interest expense was incurred.
Based on the above provision, there are three points to note:
- Deadline: Continuous service not exceeding 5 years, starting from the following year the year in which the disallowed portion of the expense arose. For example, the disallowed portion for 2026 is carried forward to 2027.
- Terms of Use: Carry forward only to the period in which the interest expense deductible for that period is less than 30% EBITDA. The total deductible amount—including the portion incurred during the period and the carried-forward portion—shall not exceed the cap for the receiving period.
- The payment period must fall within the applicable scope: The carryover is applied when determining the total deductible interest expense. Therefore, the company must confirm whether any related-party transactions occurred during the period before applying the carryover amount as a deduction.
Appendix I of Decree 255 requires the detailed reporting of carryover amounts by year of occurrence, from year (n-1) to year (n-5), in item (15). The ratio calculated after adding the carryover amounts is reported in item (16). Therefore, accountants must maintain a separate ledger for each year in which the amount arose, similar to the tracking of carried-forward losses, clearly recording the amount incurred, the amount used in each period, and the expiration year.
Regarding the transition period: If a business is eligible for the transition period under Article 3 of Decree No. 20/2025/ND-CP, it shall continue to be subject to the transition period for the remaining duration as provided for in Article 3 of Decree No. 20/2025/ND-CP.
Exceptional cases where interest expense limits do not apply.
Not all loans are subject to the 30% EBITDA rule. Point c of Paragraph 3 of Article 16 of Decree No. 255/2026/ND-CP provides:
- A loan to a taxpayer from a credit institution as defined in the Law on Credit Institutions No. 32/2024/QH15 (as amended and supplemented by Law No. 96/2025/QH15);
- Conducting insurance business in accordance with the Insurance Business Law No. 08/2022/QH15 (as amended and supplemented by Law No. 139/2025/QH15);
- Official development assistance (ODA) loans and preferential government loans are implemented through a method where the government borrows from foreign sources and then lends to businesses.;
- Loans for implementing national target programs (new rural development program and sustainable poverty reduction program);
- Loans for investment in programs and projects implementing the State's social welfare policies (resettlement housing, housing for workers and students, social housing, and other public welfare projects).
To qualify for an exemption based on the source of funds, a business must maintain complete records, project approval documents, and clearly demonstrate the intended use of the borrowed funds. If supporting documentation is missing, the tax authority has the right to deny the exemption.
Common mistakes that lead to inspection risks.
In our consulting practice, MAN – Master Accountant Network has identified common mistakes that lead to significant tax arrears for businesses, related to the calculation of deductible interest expenses:
Misunderstanding the scope of application (Independent Loan)
The biggest mistake is to assume that interest on bank loans (from independent parties) is not subject to restrictions. Point a of Paragraph 3 of Article 16 imposes restrictions total interest expense of the taxpayer, regardless of the source of the loan. Once a business engages in related-party transactions, the total interest expense (from bank loans, personal loans, and loans from the parent company) must be included in the formula. Only the items specified in point c above may be excluded.
Adjustment for Deposit Interest Errors
There are two common errors. First, companies deduct interest on deposits from interest expense but add gross interest expense to EBITDA, thereby inflating the EBITDA figure. Second, companies mistakenly classify foreign exchange gains and dividends under the “interest on deposits and loans” category.
Negative or excessively low EBITDA
For newly established businesses or those suffering heavy losses, a negative net profit can drive EBITDA down to very low levels. When EBITDA is zero or negative, there is no remaining room under the deduction cap, so all net interest expenses for that year are excluded. This amount is carried forward to subsequent periods for a maximum of five consecutive years starting from the year following the year in which it arose.
Failure to separate capitalized interest expense.
Many companies do not separately identify the portion of interest expense that is being capitalized into assets (construction in progress). Since this portion of interest expense has not been recognized as an expense for the period, it is not included in the calculation of the 30% EBITDA figure.
Strategies for optimizing interest costs for FDI enterprises.
To minimize their tax liability, businesses should proactively implement management strategies early on rather than waiting until the tax filing deadline.
Capital structure transformation (From debt to equity)
If the projected EBITDA is not high enough to cover interest expenses, the company may consider converting a portion of its debt into paid-in capital. This both reduces net interest expenses and improves the financial statements for credit purposes.
Strictly control interest rates on deposits and loans.
Interest income from deposits and loans earned during the period directly reduces net interest expense. Optimizing this revenue stream helps businesses stay within a safe range. At the same time, businesses should avoid the situation of taking on large loans while maintaining large deposit balances, which results in an unfavorable interest rate spread.
Create professional related-party transaction records.
National Files (Local Files) and Corporate Files (Master Files) are not only compliance obligations but also a shield that protects businesses. In complex cases, businesses should turn to specialized, experienced firms such as MAN – Master Accountant Network To ensure the objectivity of transactions, always adhere to the arm's length principle of interest rates and the nature of the loan, avoiding disruption caused by tax authorities reassessing figures. How to calculate deductible interest expense of the unit. Proactive consultation. related party transaction documentation service Obtaining professional services from reputable firms will help businesses minimize the risk of tax reassessments.
Conclude
Decree No. 255/2026/NĐ-CP maintains the 30% EBITDA threshold but provides greater clarity on how to identify related-party relationships, how to report the interest expense ratio in Appendix I, and the monitoring of annual carryovers. Correctly determining the calculation of deductible interest expenses is a core requirement for ensuring financial stability and tax compliance starting with the 2026 tax year.
Contact MAN – Master Accountant Network for free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network. He is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about How to Calculate Deductible Interest Expense
If my business is operating at a loss, how is the interest rate ceiling calculated?
If the loss results in a pre-tax EBITDA of zero or a negative amount, the amount of net interest expense deductible for the period is zero. The entire amount of net interest expense that is disallowed is carried forward to subsequent tax periods in accordance with Point b, Clause 3, Article 16 of Decree 255/2026/NĐ-CP. The carryforward period shall not exceed five years, starting from the year following the year in which the loss occurred.
Can interest earned on deposits be offset against interest expenses on bank loans?
Yes. According to Point a, Clause 3, Article 16 of Decree 255/2026/NĐ-CP, total interest expense is reduced by interest on deposits and interest on loans accrued during the period when compared to the 30% EBITDA figure. Only interest on deposits and interest on loans may be offset; foreign exchange gains or losses, dividends, and other financial income may not be offset.
Do I need to submit an addendum regarding interest payments if there are no related-party transactions?
No. Decree No. 255/2026/ND-CP applies to taxpayers who engage in transactions with related parties as defined in Article 5 (Article 2). If there are no related-party relationships or related-party transactions, the business is not required to file Schedule I and is not subject to the 30% EBITDA cap. The business should still maintain records demonstrating that it falls outside the scope of Article 5.
Are businesses exempt from preparing transfer pricing documentation required to determine the price of related-party transactions still required to apply the 30% EBITDA ratio?
Yes. Clause 3 of Article 20 of Decree No. 255/2026/ND-CP stipulates that taxpayers who are exempt from filing a tax return and from preparing a transfer pricing documentation file shall still determine the total deductible interest expenses in accordance with Clause 3 of Article 16.