





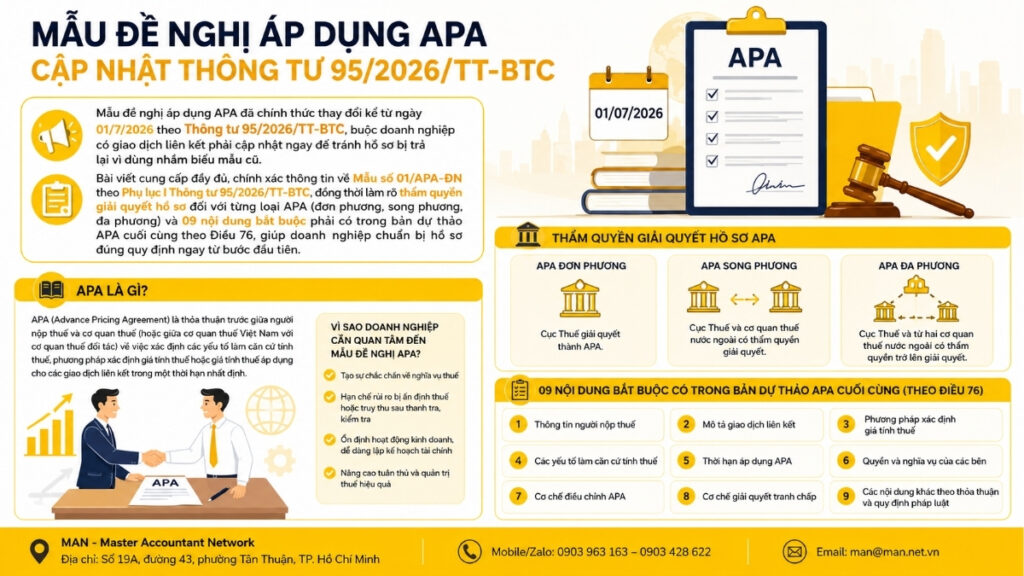
The APA application form has officially changed since July 1, 2026. Circular 95/2026/TT-BTC, This requires businesses with related-party transactions to update their forms immediately to avoid having their applications rejected due to using outdated templates. The article provides complete and accurate information about Form 01/APA-DN according to Appendix I of Circular 95/2026/TT-BTC, and clarifies the authority to process applications for each type of APA (unilateral, bilateral, multilateral) and the nine mandatory contents that must be included in the final draft APA according to Article 76, helping businesses prepare their applications correctly from the very first step.
What is an APA and why should businesses care about the APA Application Form?
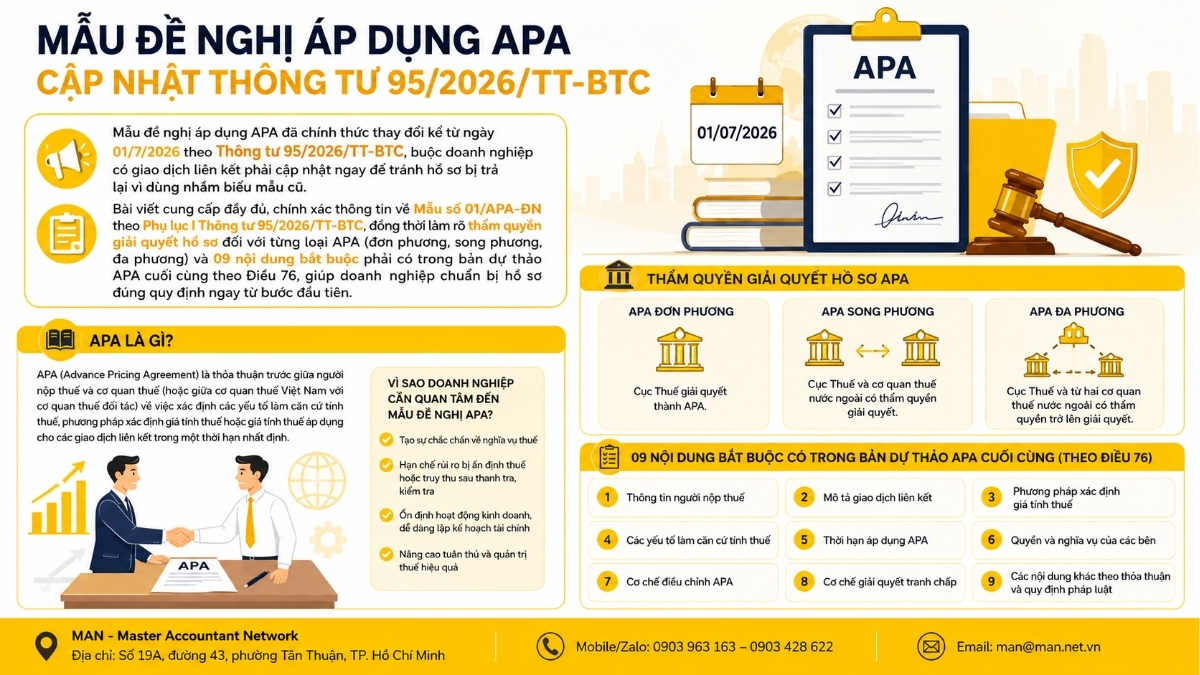
An APA (Advance Pricing Agreement) is a pre-agreement between a taxpayer and the tax authority (or between the Vietnamese tax authority and a partner tax authority) regarding the determination of factors used to calculate tax, the method of determining the taxable price, or the taxable price applicable to related-party transactions for a specified period. This is a tool used by many multinational corporations and businesses with large related-party transactions to ensure tax compliance, limit the risk of being assessed for tax arrears, or face tax recovery after audits or inspections.
To initiate this process, the first and mandatory step is for the business to prepare and submit an APA application form to the competent tax authority. This legal document lays the foundation for the entire process of exchanging, negotiating, and signing the APA later on; therefore, using the correct form and current template is crucial to the validity of the application.
In reality, many businesses face difficulties right from the data preparation stage, analyzing related-party transactions before drafting the application form; therefore, seeking assistance is essential. related party transaction advisory services Consulting with specialized and experienced units like MAN – Master Accountant Network will help businesses shorten preparation time and increase the accuracy of their documentation.
Legal basis for the Application Form for APA Implementation from July 1, 2026
According to current regulations, the application form for APA application from July 1, 2026, is Form No. 01/APA-DN, as stipulated in Appendix 1 issued with Circular 95/2026/TT-BTC.
Businesses need to pay special attention to the following: Circular 95/2026/TT-BTC is a guiding document on tax agreements, bilateral agreement procedures (MAPs), and APAs, and replaces the previous Circulars 205/2013/TT-BTC and 45/2021/TT-BTC. In other words, from the effective date of Circular 95/2026/TT-BTC, all forms related to APA applications, including the application form for APA, must be prepared according to the Appendix attached to this new circular, instead of the forms stipulated in the two previous circulars.
Having a firm grasp of this legal basis helps businesses:
- Avoid using outdated forms, as this can lead to your application being returned or requiring additional information, slowing down the APA negotiation process.
- Actively update yourself on other relevant changes in Circular 95/2026/TT-BTC, as this is the fundamental document governing the entire APA process from application submission to signing and circulation.
See also: Full text of Circular 95/2026/TT-BTC.
Form and content of Form No. 01/APA-DN
Form 01/APA-DN, the application form for APA under the new regulations, is designed to provide tax authorities with sufficient initial information to assess the feasibility of negotiating an APA with taxpayers. In principle, when completing this form, businesses must fill in all information completely and accurately according to the form issued in Appendix I of Circular 95/2026/TT-BTC, without arbitrarily changing the structure or omitting any mandatory information.
Businesses wishing to implement an APA (whether unilateral, bilateral, or multilateral) begin the process by completing the APA application form and submitting it to the competent tax authority. This is the initial step, laying the foundation for the entire subsequent APA review, analysis, and negotiation process.
Download Form No. 01/APA-DN:
Jurisdiction for processing applications for APA application
After a company submits its APA application, a crucial question arises:
Which agency has the authority to receive and process this application?
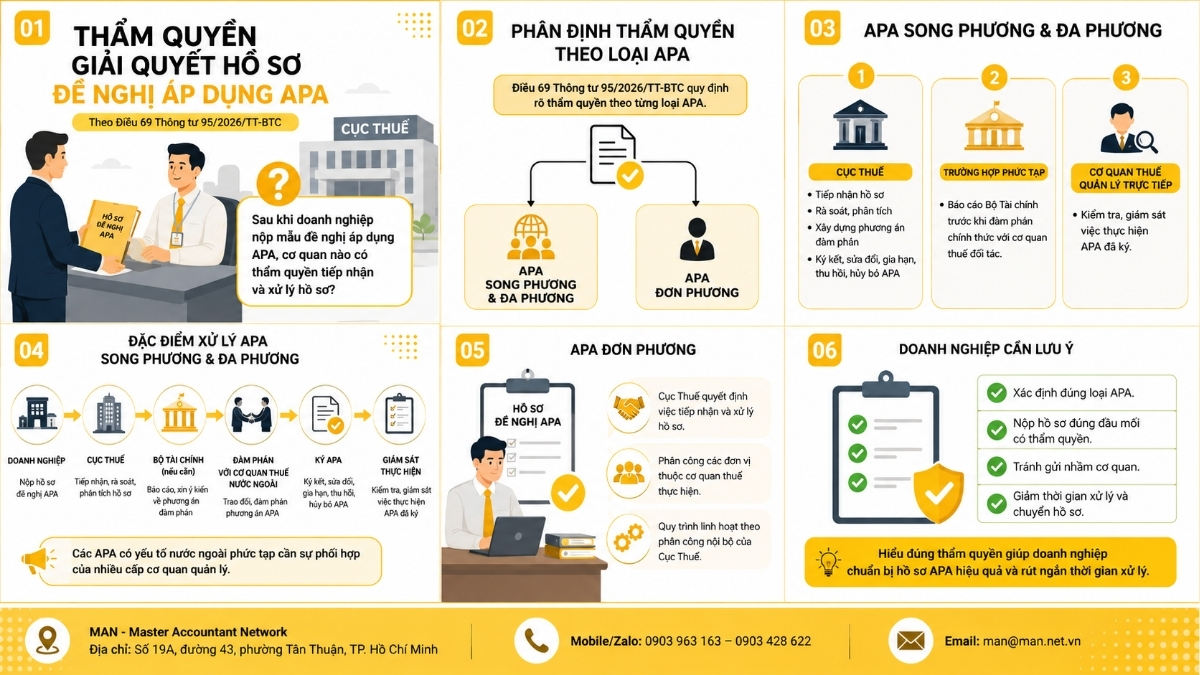
According to Article 69 of Circular 95/2026/TT-BTC, the authority to process APA applications is clearly defined for each type of APA.
For bilateral and multilateral APAs
For bilateral and multilateral APAs, i.e., those involving foreign partner tax authorities, the jurisdiction is defined as follows:
- The Tax Department is the lead agency responsible for receiving, reviewing, analyzing, and developing plans for negotiating, signing, amending, extending, revoking, and canceling APAs.
- In cases where the APA is complex, involves multiple countries, or relates to matters under the purview of various government agencies, the Tax Department must report to the Ministry of Finance to seek guidance on the APA negotiation plan before engaging in formal discussions and negotiations with the partner tax authority.
- The tax authority directly managing the taxpayer requesting the APA is responsible for inspecting and monitoring the implementation of the signed APA.
As can be seen, the process of handling bilateral and multilateral APA applications requires close coordination among multiple levels of tax authorities, especially when related-party transactions have complex foreign elements or involve various other areas of state management.
For unilateral APA
Unlike bilateral and multilateral APAs, for unilateral APAs, the authority to receive, review, analyze, and process applications for unilateral APAs is decided and assigned by the Tax Department to its subordinate units in accordance with regulations. This means that the process for handling unilateral APAs is more flexible, depending on the internal assignments of the Tax Department.
Understanding the competent authority for handling the aforementioned application helps businesses identify the correct point of contact to submit the APA application form, thereby avoiding wasting time sending it to the wrong agency or having to wait for the application to be transferred between different units.
What should the final draft APA include?
After the APA application form is approved by the tax authority, the business and the tax authority (or relevant tax authorities in the case of bilateral or multilateral agreements) will proceed to the stage of reviewing, analyzing, and negotiating the specific content of the agreement. According to Article 76 of Circular 95/2026/TT-BTC, the draft APA, after being fully agreed upon by the tax authority and the taxpayer or relevant tax authorities, is called the final draft and is signed and circulated.
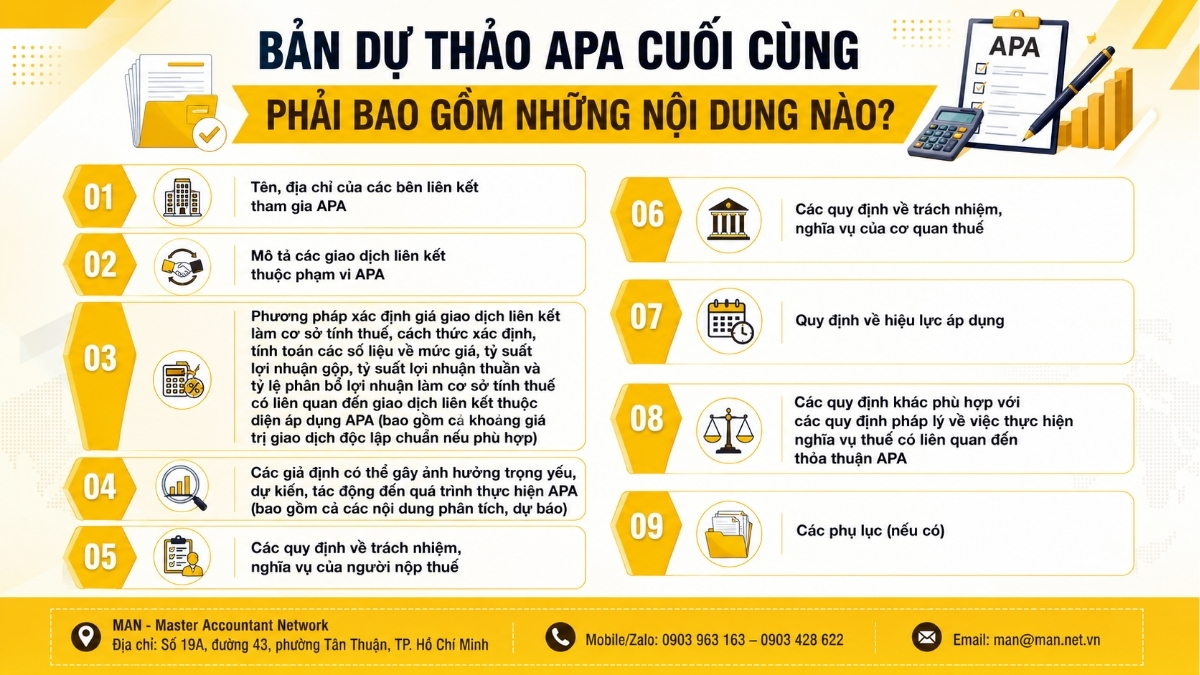
Pursuant to Clause 2, Article 76 of Circular 95/2026/TT-BTC, the final draft APA must include at least the following contents:
- Names and addresses of affiliated parties Join APA;
- Describe the related transactions. falls within the scope of the APA;
- Methods for determining transfer pricing As a basis for tax calculation, the method of determining and calculating figures on price levels, gross profit margins, net profit margins, and profit allocation ratios as a basis for tax calculation related to related-party transactions subject to APA (including the standard independent transaction value range if applicable);
- Assumptions This could have a material, anticipated, or impactful effect on the implementation of the APA (including analysis and forecasting content);
- Regulations regarding the responsibilities and obligations of taxpayers.;
- Regulations regarding the responsibilities and obligations of tax authorities.;
- Regulations regarding effective date;
- Other regulations In accordance with legal regulations regarding the fulfillment of tax obligations related to the APA agreement;
- Appendices (if any).
This is crucial and mandatory content that the initial information in an APA application should focus on. Therefore, right from the application stage, businesses should carefully prepare data on related-party transactions, the expected valuation method, and business assumptions that may affect the future implementation of the APA. Thorough preparation from the outset will significantly shorten negotiation time and increase the likelihood of reaching an APA agreement that aligns with the company's actual operations.
Some notes on preparing and submitting the APA Application Form.
To ensure a smooth submission and processing of the APA application, businesses should note the following points:
- Prepare complete data on related-party transactions. Before filling out the form, include information about related parties, the nature of the transaction, the expected valuation method, and relevant supporting documents.
- Identify the correct type of APA. (unilateral, bilateral, or multilateral) whichever type the business wishes to apply for, as each type will have different receiving authorities and processing procedures as analyzed above.
- Use the correct form 01/APA-DN Issued together with Appendix I of Circular 95/2026/TT-BTC, avoid using old forms that are no longer valid according to Circular 205/2013/TT-BTC or Circular 45/2021/TT-BTC.
- Closely monitor the progress of file processing., Actively cooperate and provide additional information and documents when requested by the tax authorities during the review and analysis of the file.
- Consult with a transfer pricing expert. For complex related-party transactions involving multiple countries, the aim is to ensure that the negotiation plan is well-structured and consistent with both Vietnamese law and international practices.
Conclude
If your business needs to learn more about and prepare documentation for an APA application, or requires a review of your current transfer pricing policy in preparation for negotiations, don't hesitate to contact us. Contact our team of affiliate marketing consultants. Contact MAN – Master Accountant Network for detailed support and to ensure compliance with Circular 95/2026/TT-BTC.
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network. He is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about the APA Application Form
What is the application form for APA implementation starting July 1, 2026?
The application form for APA implementation from July 1, 2026, is Form No. 01/APA-DN, as stipulated in Appendix I issued with Circular 95/2026/TT-BTC.
Who has the authority to handle bilateral and multilateral APA applications?
The Tax Department is responsible for receiving, reviewing, analyzing, and developing plans for negotiating, signing, amending, extending, revoking, and canceling APAs. In complex cases involving multiple countries or government agencies, the Tax Department must report to the Ministry of Finance for guidance before formal negotiations begin.
Who has the authority to process unilateral APA applications?
The authority to receive, review, analyze, and process unilateral APA applications is determined and assigned by the Tax Department to relevant units within the tax authority in accordance with regulations.
Which document does the current APA application form replace?
Circular 95/2026/TT-BTC, the document issuing the current APA application form, replaces Circular 205/2013/TT-BTC and Circular 45/2021/TT-BTC.
What should the final draft APA include?
The final draft APA must include at least nine sections: names and addresses of related parties; description of the related-party transaction; method of determining the price of the related-party transaction; material assumptions; taxpayer's responsibilities; tax authority's responsibilities; effective date; other relevant provisions; and appendices (if any).