

The EBITDA formula is considered an important indicator to evaluate core operating efficiency, eliminating the impact of interest expenses and depreciation. According to international standards, the EBITDA formula is calculated as follows:
- From operating profit (EBIT):
| EBITDA = EBIT + Depreciation Expense + Installment Payments |
In which EBIT:
| EBIT = Earnings before tax + Interest expense + Taxes |
- Profit before tax:
| EBITDA = Earnings before tax + Interest expense + Depreciation |
- Profit after tax:
| EBITDA = Net Profit + Corporate Income Tax + Interest Expense + Depreciation |
This index not only helps managers understand the profitability of core activities, but is also a measure that investors and credit institutions often use when comparing businesses in the same industry.
What is EBITDA?
EBITDA is an important financial indicator that reflects the ability of a business to generate profits from its core business activities, without taking into account financial or accounting factors such as corporate income tax, interest expense, depreciation and asset allocation. By eliminating these factors, EBITDA allows managers and investors to focus on evaluating the actual operating results and profitability of the business's core activities, instead of being influenced by tax policy or capital structure.
EBITDA is an acronym for Earnings Before Interest, Taxes, Depreciation and Amortization, which means earnings before interest, taxes, depreciation of tangible and intangible assets. Specifically:
- Earnings Before Interest: Is the profit of an enterprise determined before deducting interest expenses arising from financial debts.
- Taxes: The amount of money a business must pay to the tax authorities.
- Depreciation: is the loss of value of tangible fixed assets (such as factories, machinery, equipment, etc.) over time, reflecting wear and tear.
- Amortization: The net decrease in value of intangible assets such as patents and trademarks over time..
In financial reporting, the EBITDA calculation formula is considered a crucial measure for evaluating a company's core operational performance. This indicator allows investors and managers to analyze the company's ability to generate actual profits without being influenced by financial factors such as interest expenses, taxes, or depreciation. Applying the correct formula not only helps businesses focus on profits from their core operations but also provides a basis for more objective comparison and evaluation of business performance among companies in the market.
The role of EBITDA in financial analysis
The EBITDA calculation formula is one of the most widely used indicators in financial analysis because it focuses on net business performance and eliminates the influence of capital structure, depreciation policies, and taxes. The table below will explain in detail the practical role of the formula:
| Role | Content |
| Performance measures | Separate the financial and non-cash accounting elements to reflect profits from core business operations. The EBITDA formula helps managers and investors answer the question: How much profit is the business actually generating before calculating interest, taxes and depreciation? |
| Industry Comparison Tool | Because it excludes interest and taxes (depending on capital structure and tax policies), the EBITDA formula is convenient when comparing companies in the same industry. Additionally, the formula is also used to compare EBITDA margin (EBITDA / Revenue) to assess the effectiveness of operating profit margins among businesses. |
| Basis of valuation | From there, investors can calculate the required EBITDA ratio and analyze the EV (Enterprise Value) ratio by taking EV / EBITDA to value the business based on its operating profitability. |
| Leverage and credit risk assessment | Ratios like Net Debt / EBITDA are used to measure a company's ability to pay its debts. Banks often use the EBITDA (or adjusted EBITDA) formula in their terms and conditions and assess breaches of terms. |
Thus, as shown in the table above, the role of the EBITDA calculation formula is not just a simple calculation, but also a financial tool that helps businesses, investors, and credit institutions accurately assess operational efficiency. When applied correctly and combined with other supporting indicators, this formula becomes an important foundation in the management, valuation, and sustainable development strategies of businesses.
For example: Sử dụng số liệu của Công ty B (phần công thức bên dưới). Giả định thêm giá trị vốn hóa thị trường 1.200 tỷ đồng, dư nợ vay 500 tỷ đồng, tiền và tương đương tiền 100 tỷ đồng.
| Index | How to calculate | Result | Cách đọc |
| EBITDA margin | 105 / 1.000 | 20.5% | Mỗi 100 đồng doanh thu tạo ra 20.5 đồng lợi nhuận hoạt động trước lãi vay, thuế và khấu hao |
| EBITDA / Chi phí lãi vay | 205 / 45 | 4.6 lần | Lợi nhuận hoạt động đủ trang trải lãi vay khoảng 4.6 lần |
| Nợ thuần / EBITDA | (500 – 100) / 205 | 1.95 lần | Cần khoảng 2 năm EBITDA để trả hết nợ |
| EV / EBITDA | (1.200 + 500 – 100) / 205 | 7.8 lần | Nhà đầu tư đang trả khoản 7.8 đồng giá trị doanh nghiệp cho mỗi đồng EBITDA |
Các chỉ số này chỉ có ý nghĩa khi đặt cạnh trung bình ngành và số liệu của chính doanh nghiệp qua nhiều kỳ.
Formula for calculating EBITDA most accurate
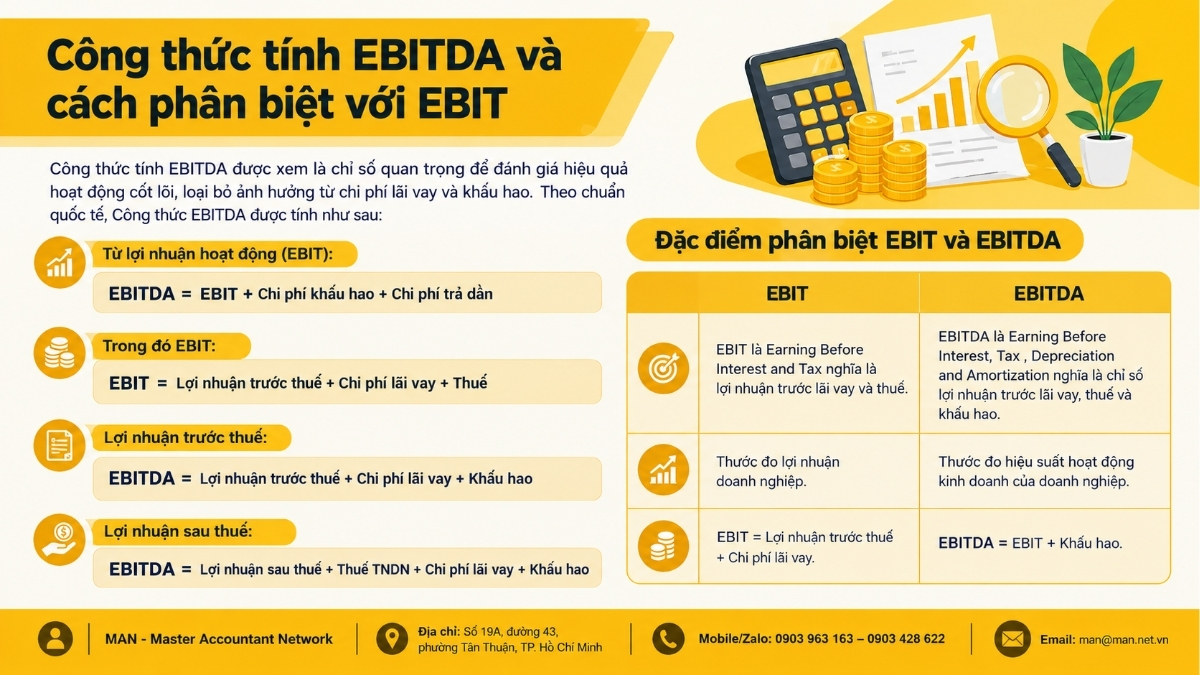
To calculate accurately, businesses can immediately apply the international standard EBITDA calculation formula below:
- From operating profit EBIT
| EBITDA = EBIT + Depreciation Expense + Installment Payments |
In which EBIT:
| EBIT = Earnings before tax + Interest expense + Taxes |
- Profit before tax
| EBITDA = Earnings before tax + Interest expense + Depreciation |
- Profit after tax
| EBITDA = Net Profit + Corporate Income Tax + Interest Expense + Depreciation |
For example: Suppose that in the fiscal year, enterprise A has information such as pre-tax accounting profit of 50 billion, interest expense of 100 billion and depreciation of 30 billion.
Apply formula number 2:
| EBITDA = Earnings before tax + Depreciation + Interest expense = 180 billion VND |
Therefore, based on the calculation formula, the EBITDA of company A is 180 billion VND.
EBIT of enterprise A:
| EBIT = Profit before tax + Interest expense = 150 billion VND. |
Thus, EBIT of enterprise A is 150 billion VND.
Case study về công thức tính EBITDA từ Báo cáo kết quả kinh doanh
Giả sử Công ty B là doanh nghiệp sản xuất, có số liệu tài chính như sau:
| Indicators | Amount (billion VND) |
| (1) Doanh thu thuần | 1000 |
| (2) Giá vốn hàng bán | 700 |
| (3) Lợi nhuận gộp = (1) – (2) | 300 |
| (4) Doanh thu hoạt động tài chính (trong đó lãi tiền gửi 4 tỷ, lãi cho vay 2 tỷ và chênh lệch tỷ giá 5 tỷ) | 10 |
| (5) Chi phí tài chính (trong đó chi phí lãi vay 45 tỷ và lỗ chênh lệch 5 tỷ) | 50 |
| (6) Chi phí bán hàng | 80 |
| (7) Chi phí quản lý doanh nghiệp | 100 |
| (8) Lợi nhuận thuần từ hoạt động kinh doanh = (3) + (4) – (5) – (6) – (7) | 80 |
| (9) Lợi nhuận khác | 20 |
| (10) Lợi nhuận kế toán trước thuế = (8) + (9) | 100 |
| (11) Chi phí thuế TNDN (giả định thuế suất 20%, không có khoản điều chỉnh) | 20 |
| (12) Lợi nhuận sau thuế = (10) – (11) | 80 |
| (13) Tổng khấu hao | 60 |
Dưới đây là cách tính và kết quả EBITDA có được:
| How to calculate | Phép tính | EBITDA (tỷ đồng) |
| Cách 1: Tính từ EBIT | EBIT = 100 + 45 = 145 EBITDA = 145 + 50 + 10 | 205 |
| Cách 2: Tính từ lợi nhuận trước thuế | 100 + 45 + 60 | 205 |
| Cách 3: Tính từ lợi nhuận sau thuế | 80 + 20 + 45 + 60 | 205 |
| Cách 4: Tính từ EBITDA hoạt đồng | 1000 – 700 – 80 – 100 + 60 | 180 |
Ba cách 1, 2 và 3 đều cho cùng kết quả: EBITDA của Công ty B là 205 tỷ đồng, EBIT là 145 tỷ đồng. Riêng cách thứ 4 cho ra kết quả EBITDA là 180 tỷ đồng.
Chênh lệch 25 tỷ đồng được giải thích đầy đủ như sau:
| Khoản chênh lệch | Amount (billion VND) |
| Doanh thu hoạt động tài chính (lãi tiền gửi, lãi cho vay, lãi tỷ giá) | 10 |
| Chi phí tài chính ngoài lãi vay (lỗ tỷ giá) | -5 |
| Lợi nhuận khác (chủ yếu từ thành lý TSCĐ | 20 |
| Total | 25 |
Khi so sánh EBITDA giữa hai doanh nghiệp hoặc hai kỳ, phải dùng cùng một cách tính. Khoản lãi thanh lý TSCĐ 25 tỷ đồng là thu nhập không lặp lại; nếu không loại ra, EBITDA sẽ đẹp hơn năng lực vận hành thực tế.
The significance of calculating EBITDA in measuring business performance.
Besides understanding what EBITDA is, managers and investors also need to master its calculation method to apply it effectively in financial analysis. This is one of the important indicators reflecting the core operational efficiency of a business, helping to eliminate the impact of interest expenses, taxes, and depreciation costs. Therefore, EBITDA shows the true business performance, supporting businesses, owners, and investors in gaining a more accurate view of production and business efficiency as well as sustainable long-term profitability.
For business owners
Mastering the formula not only helps businesses understand the nature of this indicator but also provides a foundation for maximizing its value in financial analysis and management. Specifically:
- Assessing a business's profitability: By eliminating factors such as interest, taxes and depreciation, EBITDA more accurately reflects the efficiency of generating profits from core production and business activities.
- Compare performance over time: Because it is not affected by fluctuations in interest rates or tax rates, business owners can easily track and compare growth over each period.
- Convincing investors: When presenting reports, EBITDA is a powerful indicator that helps businesses convey a positive picture of financial health and operating capacity, thereby increasing investor confidence.
For investors
To maximize the value from the EBITDA calculation formula, investors and managers often apply this index in many important aspects of business analysis:
- Assessing cash flow generation: EBITDA is a useful tool to determine the profitability of core operations, thereby considering the ability to quickly pay back capital and long-term growth potential.
- Comparing companies within the same industry: By removing the impact of taxes and interest, EBITDA makes comparing performance between companies more transparent and objective.
- Estimating Enterprise Value: Popular valuation metrics such as EV/EBITDA are often used to determine fair value, helping investors identify whether a business is overvalued or undervalued relative to its intrinsic value.
Although commonly used in financial analysis, many people still easily confuse EBITDA and EBIT because both indicators reflect profits from business operations. However, to understand the true nature and avoid inaccuracies in evaluating business performance, it is necessary to clearly distinguish between EBIT and EBITDA.
Distinguishing features of EBIT and EBITDA
Once you understand the concept of EBITDA and the detailed formula, differentiating between EBITDA and EBIT becomes simpler. Although these two indicators have many similarities, they are often compared to comprehensively assess a company's performance. The table below illustrates the differences between these two indicators:
| EBIT | EBITDA |
| EBIT is Earning Before Interest and Tax. | EBITDA is Earning Before Interest, Tax, Depreciation and Amortization which means the index of profit before interest, tax and depreciation. |
| Measure of corporate profits. | Measure of business performance of an enterprise. |
| EBIT = Earnings before tax + Interest expense. | EBITDA = EBIT + Depreciation. |
From the comparison table above, it can be seen that both EBIT and EBITDA are important metrics for analyzing corporate finance, but each serves a different purpose. While EBIT focuses on profit before interest and taxes, EBITDA reflects core operating performance by excluding depreciation. Understanding this difference helps managers and investors apply the correct metric in each situation, thereby making more accurate decisions.
So why is EBITDA considered an accurate measure of business performance?
Because EBITDA excludes factors not directly related to core business operations, such as interest expense, corporate income tax, or depreciation expense. These factors may vary depending on financial policies, capital structure, or legal regulations in each country, but they do not reflect the true nature of a company's operational capabilities.
Focusing solely on the results generated from core business operations helps managers and investors clearly see the true effectiveness of revenue generation. For example, two companies in the same industry may differ in debt ratios or depreciation policies, leading to differences in net profit. However, comparing them using EBITDA will reveal which company operates more efficiently, regardless of differences in capital or financial strategies.
In other words, EBITDA is a "fair measure" for evaluating business performance, helping to eliminate distortions from external factors and providing a more honest view of the internal operational strength of the business.
Reference: How to calculate interest expense according to Decree 255.
Example: Giả sử Công ty X và Công ty Y cùng sản xuất bao bì, cùng doanh thu và cùng hiệu quả vận hành. Lợi nhuận hoạt động trước lãi vay và khấu hao của mỗi công ty đều là 100 tỷ đồng. Khác biệt nằm ở cách tài trợ vốn và tài sản. Số liệu như sau:
- Công ty X dùng vốn chủ sở hữu, máy móc đã cũ, khấu hao 20 tỷ đồng/năm
- Công ty Y vay ngân hàng để mua dây chuyền mới, chi phí lãi vay 30 tỷ đồng/năm, khấu hao 35 tỷ đồng/năm
Giả định thuế suất thuế TNDN 20% và không có khoản điều chỉnh thuế (đơn vị: tỷ đồng):
| Indicators | Công ty X | Công ty Y |
| Lợi nhuận trước lãi vay, khấu hao | 100 | 100 |
| Khấu hao | 20 | 35 |
| EBIT | 80 | 65 |
| Interest expense | 0 | 30 |
| Profit before tax | 80 | 35 |
| Thuế TNDN 20% | 16 | 7 |
| Profit after tax | 64 | 28 |
| EBITDA = Lợi nhuận trước thuế + Lãi vay + Khấu hao | 100 | 100 |
Nhìn lợi nhuận sau thuế, Công ty X có vẻ hiệu quả gấp hơn 2 lần Công ty Y. Nhìn EBIT, X vẫn hơn Y 15 tỷ đồng do khấu hao thấp hơn. Nhưng EBITDA của hai công ty bằng nhau, cho thấy năng lực vận hành thực chất là như nhau; khác biệt đến từ quyết định tài trợ vốn và chu kỳ đầu tư tài sản.
Nói cách khác, EBITDA chính là thước đo để đánh giá hiệu năng kinh doanh, giúp loại bỏ nhiễu từ cấu trúc vốn và chính sách khấu hao.
EBITDA tài chính khác EBITDA thuế theo Nghị định 255/2026/NĐ-CP như thế nào?
Với doanh nghiệp có giao dịch liên kết, EBITDA không chỉ là chỉ số phân tích mà còn quyết định trực tiếp số thuế phải nộp. Theo điểm a khoản 3 Điều 16 Nghị định 255/2026/NĐ-CP, tổng chi phí lãi vay sau khi trừ lãi tiền gửi và lãi cho vay phát sinh trong kỳ được trừ khi tính thuế TNDN không vượt quá 30% của tổng: lợi nhuận thuần từ hoạt động kinh doanh + chi phí lãi vay sau khi trừ lãi tiền gửi và lãi cho vay + chi phí khấu hao phát sinh trong kỳ.
Có thể viết gọn:
Chi phí lãi vay thuần = Chi phí lãi vay – (Lãi tiền gửi + Lãi cho vay) |
Cách xác định EBITDA thuế:
Taxable EBITDA = Net operating profit + Net interest expense + Depreciation expense |
Chi phí lãi vay thuần được trừ:
Chi phí lãi vay thuần tối đa được trừ = 30% x EBITDA thuế |
Dưới đây là bảng so sánh giữa EBITDA tài chính và EBITDA thuế theo Nghi định 255/2026/NĐ-CP:
| Criteria | EBITDA tài chính (phân tích, định giá) | Taxable EBITDA |
| Điểm xuất phát | Profit before tax | Lợi nhuận thuần từ hoạt động kinh doanh (không gồm lợi nhuận khác) |
| Lãi vay cộng lại | Chi phí lãi vay gộp | Net interest expense (after deducting interest on deposits and loans) |
| Khấu hao | Khấu hao TSCĐ hữu hình và vô hình | Depreciation expense incurred during the period |
| Purpose | Đánh giá hiệu quả, định giá, tín dụng | Xác định chi phí lãi vay được trừ khi tính thuế TNDN |
Example: Giả sử Công ty B (giữ nguyên số liệu đã nêu trên) có quan hệ liên kết và phát sinh giao dịch liên kết trong kỳ như sau (đơn vị: tỷ đồng).
| Step | Phép tính | Result |
| Net interest expense | 45 – (4 + 2) | 39 |
| Taxable EBITDA | 80 + 39 + 60 | 179 |
| Ngưỡng 30% | 30% x 179 | 53.7 |
| So sánh | 39 < 53.7 | Không vượt ngưỡng, toàn bộ 39 tỷ được trừ |
Note: Lãi chênh lệch tỷ giá 4 tỷ đồng Are not được bù trừ vào chi phí lãi vay, vì điểm a khoản 3 Điều 16 chỉ cho trừ lãi tiền gửi và lãi cho vay.
EBITDA thuế (179 tỷ) thấp hơn EBITDA tài chính (205 tỷ) đúng 26 tỷ đồng, gồm: lợi nhuận khác 20 tỷ (không nằm trong lợi nhuận thuần từ hoạt động kinh doanh) và lãi tiền gửi, lãi cho vay 6 tỷ (đã được trừ khi tính lãi vay thuần).
Dùng nhầm EBITDA tài chính, doanh nghiệp khai thiếu chi phí bị loại
Giữ nguyên các số liệu khác của Công ty B, nhưng giả sử công ty vay thêm từ công ty mẹ ở nước ngoài, chi phí lãi vay tăng từ 45 lên 70 tỷ đồng. Khi đó lợi nhuận thuần từ hoạt động kinh doanh giảm 25 tỷ, còn 55 tỷ đồng; lợi nhuận trước thuế còn 75 tỷ đồng.
| Indicators | Taxable EBITDA | EBITDA tài chính |
| Net interest expense | 70 – 6 = 64 | 70 – 6 = 64 |
| EBITDA | 55 + 64 + 60 = 179 | 75 + 70 + 60 = 205 |
| Ngưỡng 30% | 53.7 | 61.5 |
| Chi phí lãi vay bị loại | 64 – 53.7 = 10.3 | 64 – 61.5 = 2.5 |
Nếu dùng EBITDA tài chính, Công ty B chỉ loại 2.5 tỷ đồng thay vì 10.3 tỷ đồng, khai thiếu 7.8 tỷ đồng chi phí không được trừ, tương ứng khoảng 1.56 tỷ đồng thuế TNDN (7.8 × 20%) bị truy thu khi thanh tra, chưa kể tiền chậm nộp và tiền phạt.
Hai chi tiết đáng chú ý từ ví dụ này:
- Khi lãi vay tăng thêm 25 tỷ, cả EBITDA tài chính và EBITDA thuế đều không đổi, đúng bản chất không phụ thuộc cấu trúc vốn của EBITDA. Điều thay đổi là chi phí lãi vay thuần và chính phần tăng thêm này bị khống chế.
- Phần 10.3 tỷ đồng bị loại không mất hẳn mà được chuyển sang kỳ tính thuế tiếp theo được quy định tại điểm b khoản 3 Điều 16 Nghị định 255/2026/NĐ-CP, với thời gian chuyển tiếp liên tục không quá 05 năm.
Cases where the EBITDA calculation formula is applied
The EBITDA calculation formula is widely used in many situations to analyze and evaluate the financial performance of businesses. Particularly in industries with a high proportion of assets and high depreciation costs, the formula is often used to reflect operating profit, helping businesses improve their financial reporting image and increase investor confidence.
Furthermore, it is an important tool for comparing the performance of businesses within the same industry or at different stages of development. This indicator often appears in EV/EBITDA valuation models and in many cases can replace cash flow in quick analysis.
Furthermore, investors and managers also utilize the formula through derived indicators such as EBITDA Margin, EBITDA/Depreciation Expense, or Debt/EBITDA, to assess the profitability, level of financial leverage, and long-term growth prospects of the business.
Advantages and disadvantages of the formula
We need to consider both the advantages and disadvantages of the formula. Like any measurement tool, the formula offers significant benefits but also has certain limitations. The table below will help distinguish the advantages and disadvantages of the EBITDA calculation formula, thereby assisting investors and businesses in using this indicator more accurately.
| Advantage | Disadvantages |
| Reflecting core business performance: The EBITDA calculation formula excludes depreciation, interest expenses, and taxes, which are not directly incurred during the period. | For businesses with high depreciation expenses, the formula can "beautify" financial statements compared to reality. |
| Focus on actual operations: Helps investors assess the ability to generate profits from core business activities. | These businesses typically have low net profits, so using a formula can mask significant financial weaknesses. |
| Support for business comparison: The EBITDA formula is applied to compare operating efficiency between businesses in the same industry, over many different periods. | Valuation can be misleading: If investors rely solely on the formula while ignoring other indicators such as cash flow or net profit, they may misjudge the true value. |
| Approaching Actual Cash Flow: Since depreciation is not a cash expense, the EBITDA formula better represents cash flow from operations. | Not a complete picture: This formula cannot replace other indicators in financial analysis, especially in asset-intensive industries. |
The EBITDA calculation formula is a useful tool for measuring business performance and comparing different companies. However, when conducting financial analysis, it is necessary to combine EBITDA calculation with net profit and cash flow to gain a comprehensive view and minimize the risk of misvaluation.
Ví dụ trường hợp EBITDA dương nhưng doanh nghiệp vẫn thiếu tiền
Công ty B có EBITDA 205 tỷ đồng (Ví dụ 1). Trong năm, công ty chi 150 tỷ đồng mua sắm máy móc để duy trì công suất, trả lãi vay 45 tỷ đồng và nộp thuế TNDN 20 tỷ đồng. Giả định vốn lưu động không thay đổi:
| Indicators | Amount (billion VND) |
| EBITDA | 205 |
| Trừ chi phí đầu tư TSCĐ | 150 |
| Trừ lãi vay đã trả | 45 |
| Trừ thuế TNDN đã nộp | 20 |
| Dòng tiền còn lại | 10 |
EBITDA 205 tỷ đồng trông rất khỏe, nhưng sau khi tính đến các khoản chi bắt buộc, công ty thiếu hụt 10 tỷ đồng và phải vay thêm hoặc dùng tiền tồn quỹ. Đây là lý do EBITDA cần được đọc cùng báo cáo lưu chuyển tiền tệ.
Công thức tính EBITDA là công cụ hữu ích để đo lường hiệu năng kinh doanh và so sánh giữa các doanh nghiệp. Tuy nhiên, khi phân tích tài chính, cần kết hợp EBITDA với lợi nhuận ròng và dòng tiền để có cái nhìn toàn diện, hạn chế rủi ro định giá sai.
Notes when applying the EBITDA calculation formula in business and investment
When applying the EBITDA calculation formula, businesses need to keep the following points in mind to ensure that the EBITDA results are effective:
- Understanding the EBITDA metric, its formula, and its meaning is crucial: EBITDA only reflects profit before accounting for factors such as interest, taxes, depreciation, and amortization. This allows businesses to focus on evaluating core operating performance, but the formula for this metric doesn't provide a comprehensive view of net profit after deducting significant financial expenses.
- Combined with other index formula analysis: The EBITDA formula is just one of many formulas to help evaluate finances. Businesses need to refer to using additional index formulas such as ROE (Return on Equity), ROA (Return on Assets) and free cash flow to help provide a more complete perspective on business performance.
- Assessing the scale, industry characteristics and business cycle: Due to the characteristics of each industry with different investment levels and depreciation costs, the use of the EBITDA calculation formula needs to be placed in the specific context of the industry and business cycle, to ensure accurate comparison between businesses in the same industry.
- Be careful when making decisions: To attract investors, some businesses may "beautify" their reports by increasing the EBITDA index. Therefore, managers need to carefully evaluate the data to avoid being led by numbers that do not reflect reality.
Reference: Interest expenses are not deductible under Decree 255/2026.
Conclude
In summary, the EBITDA formula is a useful tool for businesses and investors to evaluate core operating performance, eliminating financial and accounting factors that interfere. However, for a more comprehensive and accurate view, EBITDA needs to be placed in the context of the industry, business cycle and combined with other financial indicators. If you are a business that wants to optimize financial reports, improve management capacity and increase investor confidence, let MAN – Master Accountant Network Accompany businesses in analyzing, consulting and implementing effective financial solutions.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network. He is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about the EBITDA Calculation Formula
What does negative EBITDA mean?
Negative EBITDA means the business is losing money at the core operating level, even before accounting for interest, taxes, and depreciation. This is a much more serious warning sign than negative net profit, because negative net profit may simply be due to high interest or depreciation expenses, while negative EBITDA indicates that the business itself is not generating cash.
What is a good EBITDA level? What is the ideal EBITDA margin?
There is no single standard EBITDA margin (EBITDA/Revenue) for all industries. Manufacturing, telecommunications, and real estate typically have margins of 20-40% (TP3T) due to capital intensity; trade and retail industries usually have margins of only 5-15% (TP3T) due to thin profit margins. The correct way to assess EBITDA is to compare a company's EBITDA margin with the industry average and with the company itself over different periods, not cross-industry comparisons.
Does EBITDA include corporate income tax?
No. EBITDA is calculated before deducting corporate income tax. If you start calculating from after-tax profit, you must add back the corporate income tax already paid along with interest expense and depreciation to arrive at the correct EBITDA figure.
What EV/EBITDA ratio is considered reasonable?
A reasonable EV/EBITDA ratio depends on the industry and growth stage: high-growth sectors (technology) are typically valued at 12-20 times, while traditional sectors (manufacturing, trading) are commonly valued at 6-10 times. A lower-than-average EV/EBITDA ratio may indicate an attractive valuation, but it could also reflect underlying risks not yet recognized by the market, requiring further analysis in relation to revenue growth and debt leverage.
EBITDA dùng để tính chi phí lãi vay được trừ có giống EBITDA trên báo cáo phân tích không?
Không. Theo khoản 3 Điều 16 Nghị định 255/2026/NĐ-CP, EBITDA dùng để khống chế chi phí lãi vay được tính từ lợi nhuận thuần từ hoạt động kinh doanh (không gồm lợi nhuận khác), cộng chi phí lãi vay pure (đã trừ lãi tiền gửi và lãi cho vay) và chi phí khấu hao. Với Công ty B, EBITDA thuế là 179 tỷ đồng, thấp hơn EBITDA tài chính 205 tỷ đồng.